Singapore Savings Bonds (SSB) Interest Rate History: The Ultimate Guide
Last updated 1 October 2026
The Singapore government offers Singapore Savings Bonds (SSB) every month. Here you will find the SSB interest rate history and everything you need to know about SSB.
SSB Interest Rate History
The table below lists the Singapore Savings Bonds / SSB interest rate history in reverse chronological order:
| Issue Date | Issue Code | First-Year Rate | Avg 10-Year Rate | Quantity Ceiling |
|---|---|---|---|---|
| 02 Nov 2026 | SBNOV26 GX26110X | 1.67% | 2.45% | - |
| 01 Oct 2026 | SBOCT26 GX26100Z | 1.65% | 2.32% | - |
| 01 Sept 2026 | SBSEP26 GX26090V | 1.52% | 2.25% | - |
| 03 Aug 2026 | SBAUG26 GX26080T | 1.46% | 2.06% | - |
| 01 Jul 2026 | SBJUL26 GX26070F | 1.46% | 2.11% | - |
| 02 Jun 2026 | SBJUN26 GX26060N | 1.46% | 2.11% | - |
| 04 May 2026 | SBMAY26 GX26050H | 1.40% | 2.14% | - |
| 01 Apr 2026 | SBAPR26 GX26040E | 1.36% | 1.99% | - |
| 02 Mar 2026 | SBMAR26 GX26030W | 1.38% | 2.16% | - |
| 02 Feb 2026 | SBFEB26 GX26020S | 1.35% | 2.25% | - |
| 02 Jan 2026 | SBJAN26 GX26010A | 1.33% | 1.99% | - |
| 01 Dec 2025 | SBDEC25 GX25120E | 1.35% | 1.85% | - |
| 03 Nov 2025 | SBNOV25 GX25110W | 1.39% | 1.83% | - |
| 01 Oct 2025 | SBOCT25 GX25100S | 1.56% | 1.93% | - |
| 01 Sept 2025 | SBSEP25 GX25090A | 1.71% | 2.11% | - |
| 01 Aug 2025 | SBAUG25 GX25080X | 1.82% | 2.29% | - |
| 01 Jul 2025 | SBJUL25 GX25070Z | 2.06% | 2.49% | - |
| 02 Jun 2025 | SBJUN25 GX25060V | 2.20% | 2.56% | - |
| 02 May 2025 | SBMAY25 GX25050T | 2.49% | 2.69% | - |
| 01 Apr 2025 | SBAPR25 GX25040F | 2.73% | 2.85% | - |
| 03 Mar 2025 | SBMAR25 GX25030N | 2.83% | 2.97% | $58,500 |
| 03 Feb 2025 | SBFEB25 GX25020H | 2.76% | 2.82% | - |
| 02 Jan 2025 | SBJAN25 GX25010E | 2.73% | 2.86% | - |
| 01 Dec 2024 | SBDEC24 GX24120F | 2.66% | 2.81% | - |
| 01 Nov 2024 | SBNOV24 GX24110N | 2.25% | 2.56% | - |
| 01 Oct 2024 | SBOCT24 GX24100H | 2.59% | 2.77% | - |
| 02 Sept 2024 | SBSEP24 GX24090E | 3.06% | 3.10% | - |
| 01 Aug 2024 | SBAUG24 GX24080W | 3.19% | 3.22% | - |
| 01 Jul 2024 | SBJUL24 GX24070S | 3.26% | 3.30% | $59,000 |
| 03 Jun 2024 | SBJUN24 GX24060A | 3.26% | 3.33% | $24,000 |
| 02 May 2024 | SBMAY24 GX24050X | 2.99% | 3.06% | - |
| 01 Apr 2024 | SBAPR24 GX24040Z | 2.95% | 3.04% | - |
| 01 Mar 2024 | SBMAR24 GX24030V | 2.74% | 2.88% | - |
| 01 Feb 2024 | SBFEB24 GX24020T | 2.72% | 2.81% | - |
| 02 Jan 2024 | SBJAN24 GX24010F | 3.00% | 3.07% | - |
| 01 Dec 2023 | SBDEC23 GX23120Z | 3.30% | 3.40% | $20,500 |
| 01 Nov 2023 | SBNOV23 GX23110V | 3.21% | 3.32% | $47,500 |
| 02 Oct 2023 | SBOCT23 GX23100T | 3.05% | 3.16% | - |
| 01 Sept 2023 | SBSEP23 GX23090F | 3.01% | 3.06% | - |
| 01 Aug 2023 | SBAUG23 GX23080N | 2.97% | 2.99% | - |
| 03 Jul 2023 | SBJUL23 GX23070H | 2.76% | 2.82% | - |
| 01 Jun 2023 | SBJUN23 GX23060E | 2.81% | 2.81% | - |
| 02 May 2023 | SBMAY23 GX23050W | 3.03% | 3.07% | - |
| 03 Apr 2023 | SBAPR23 GX23040S | 3.01% | 3.15% | $68,500 |
| 01 Mar 2023 | SBMAR23 GX23030A | 2.76% | 2.90% | - |
| 01 Feb 2023 | SBFEB23 GX23020X | 2.84% | 2.97% | - |
| 03 Jan 2023 | SBJAN23 GX23010Z | 2.95% | 3.26% | $172,500 |
| 01 Dec 2022 | SBDEC22 GX22120S | 3.26% | 3.47% | $14,000 |
| 01 Nov 2022 | SBNOV22 GX22110A | 3.08% | 3.21% | $10,000 |
| 03 Oct 2022 | SBOCT22 GX22100X | 2.60% | 2.75% | $42,000 |
| 01 Sept 2022 | SBSEP22 GX22090Z | 2.63% | 2.80% | $13,000 |
| 01 Aug 2022 | SBAUG22 GX22080V | 2.00% | 3.00% | $9,000 |
| 01 Jul 2022 | SBJUL22 GX22070T | 1.69% | 2.71% | $18,000 |
| 01 Jun 2022 | SBJUN22 GX22060F | 1.43% | 2.53% | $15,000 |
| 04 May 2022 | SBMAY22 GX22050N | 0.86% | 2.09% | - |
| 01 Apr 2022 | SBAPR22 GX22040H | 0.71% | 1.91% | - |
| 01 Mar 2022 | SBMAR22 GX22030E | 0.59% | 1.79% | - |
| 03 Feb 2022 | SBFEB22 GX22020W | 0.52% | 1.64% | - |
| 03 Jan 2022 | SBJAN22 GX22010S | 0.45% | 1.78% | - |
| 01 Dec 2021 | SBDEC21 GX21120H | 0.41% | 1.71% | - |
| 01 Nov 2021 | SBNOV21 GX21110E | 0.34% | 1.45% | - |
| 01 Oct 2021 | SBOCT21 GX21100W | 0.35% | 1.39% | - |
| 01 Sept 2021 | SBSEP21 GX21090S | 0.35% | 1.43% | - |
| 02 Aug 2021 | SBAUG21 GX21080A | 0.34% | 1.50% | - |
| 01 Jul 2021 | SBJUL21 GX21070X | 0.36% | 1.53% | - |
| 01 Jun 2021 | SBJUN21 GX21060Z | 0.38% | 1.61% | - |
| 03 May 2021 | SBMAY21 GX21050V | 0.37% | 1.56% | - |
| 01 Apr 2021 | SBAPR21 GX21040T | 0.35% | 1.15% | - |
| 01 Mar 2021 | SBMAR21 GX21030F | 0.28% | 0.97% | - |
| 01 Feb 2021 | SBFEB21 GX21020N | 0.32% | 0.89% | - |
Source: MAS
Contents
What is Singapore Savings Bond (SSB)?
Singapore Savings Bond (SSB) is a unique long-term 10-year Singapore government bond fully backed by the Singapore government. Your principal and interest payouts are guaranteed.
SSB differs from other Singapore government securities: you can redeem partially or in full at any month without penalty. You even earn the accrued interest up to the time of redemption.
SSB always offers step-up interest rates to encourage long-term holding. The first-year interest rate will be lower or equal to the second-year rate, with the last-year rate being the highest. SSB interest rates are pre-determined for the whole duration at the time of issuance. Investors will receive interest payouts every six months.
SSB is a unique offering from the Singapore government for retail investors to encourage long-term saving. Note that there is a maximum holding limit of $200,000 in total.
Pros and Cons of SSB (Singapore Savings Bonds)
These are the main features of SSB:
Pros #1: Low-risk
Like other government bonds, your initial principal and interest payouts are guaranteed with SSB. The Singapore government fully backs SSB. It is among the few countries with the highest credit rating in the world. Therefore, SSB suits investors with lower risk-profile who seek capital preservation.
Pros #2: Long-term
SSB is a long-term ten-year bond. You are guaranteed the payout for ten years. The SSB interest rate is unique because it always steps up yearly for the whole bond’s duration. The first year being the lowest and the 10th year being the highest. The steps-up interest rates encourage investors to keep holding for longer.
Pros #3: Flexible
Flexibility is the main benefit of SSB. You can redeem your investment any month without penalty and still earn the accrued interest. You just have to pay a $2 transaction fee (both for application and redemption). Because of this flexibility, you can also use SSB as a short-term instrument to park your cash in the short-term.
Cons #1: Lower 1st-Year Rate
Because of the step-up SSB interest rates, the first-year interest rate is always the lowest. The government may adjust the rate offering to account for this unique requirement to create these step-up rates. As a result, the first-year interest rate may not be as competitive as short-term bonds. If you plan to hold just for the short term and are okay with locking your cash for a fixed duration (6 months or one year), you may consider T-bill instead.
Cons #2: Maximum Holding
If SSB sounds too good to be true, yes, there is a catch… There is a maximum total holding of $200,000 per individual. You can apply or redeem anytime, but the total holding should not exceed $200,000. Although this ceiling is relatively high, some may still find it limiting.
Cons #3: Relatively Low Return
As with other fixed-income investments, SSB interest rates are relatively low and may not beat inflation. This is why SSB is ideal for investors with the lowest risk profile who seek capital preservation.
Singapore Savings Bonds (SSB) Alternatives
The SSB interest rate history above may look attractive. But how does SSB stack up against other fixed-income alternatives?
SSB vs. SGS Bonds
The main alternative to SSB is the SGS Bonds. Both are long-term Singapore government bonds. Unlike SSB, which has a uniform maturity of ten years, SGS bonds have different maturities, such as 2, 5, 10, 15, 20, 30, or 50 years.
SGS Bonds have fixed interest rates for the whole duration of the bonds. It is determined from the auction result.
On the other hand, SSB has steps-up interest rates with the rates already pre-determined before the allotment date. SGS bonds usually have slightly more competitive rates than SSB in the beginning. But the return will be comparable if you hold the SSB until maturity.
SGS doesn't allow early redemption but allows secondary market trading. With secondary market trading, there is a chance investors may lose on the initial principal due to the bond and interest rate market dynamics. SSB investors do not need to worry about this because they can redeem at any month without penalty. SSB is just more flexible and liquid.
Investors who prefer more competitive rates and do not mind the lock-up period of the bond may consider SGS bonds. But for most retail investors who prefer flexibility, SSB is the more attractive choice.
SSB vs. T-bill
SSB is a long-term 10-year bond, while T-bill is a short-term 6-month or 1-year bond. However, due to the flexibility of SSB, some investors use SSB as a short-term instrument. If we compare the interest rate of SSB and T-bill for the short term, they should be in line with each other except during times of economic uncertainty.
In an uncertain economic condition, the yield curve is inverted. When the yield curve is inverted, shorter-term bonds yield higher than longer-term bonds. The bad news is that SSB has steps-up interest rates, therefore, cannot benefit from these higher shorter-term rates. In this economic scenario, T-bill will offer better rates in the short term. In normal economic conditions, both should offer comparable rates, and some investors may prefer SSB due to its flexibility to redeem every month.
SSB vs. Fixed Deposits
Like T-bills, fixed deposits usually have short-term maturity, ranging from 3 to 24 months. SSB generally provides more liquidity due to its monthly redemption. However, in the short term, there is a chance that SSB yields much lower than fixed deposits if the yield curve is inverted. You can check Singapore's latest fixed deposit rates and compare them to the SSB offering to see which suits you better. If you are okay with locking your cash for the duration of the deposit, fixed deposits may be a good choice for parking cash in the short term.
How are SSB Interest Rates Determined?
SSB has step-up interest rates, meaning the first year rate is the lowest and the last year’s rate is the highest. The longer we hold the bond, the higher our effective interest rate is.
Each SSB issuance interest rate is based on the average SGS Bond yields the month before the SSB application date.
Here is the formula to determine the SSB rates:
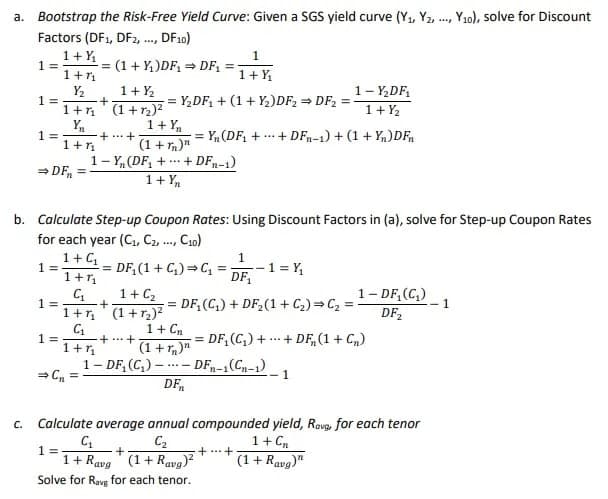
Source: MAS
Because SSB has step-up interest rates, there could be cases where they must be manually adjusted to enforce their step-up nature.
In a normal economic condition, the short-term rates are usually lower than the long-term rates. This is because there are more risks in holding long-term bonds. In this case, the step-up nature of SSB rates is already there without any manual intervention.
However, short-term rates may be higher in an uncertain economic condition than longer-term ones. This phenomenon is called an inverted yield curve. In this scenario, the rates do not step up by default. MAS will need to manually adjust the rates, lowering the shorter-term rates to ensure the final SSB offering has step-up rates.
This is why you may have experienced a situation where SSB offers a 2.8% interest rate for the first year, but short-term bonds (T-bill) or cash management accounts offer 4%. But if you hold the SSB until maturity, your effective interest rate will be comparable to the 10-year yield in SGS bonds. You will have a lower effective interest rate if you redeem your SSB in the early years, way before maturity. This encourages investors to save for the long term.
How to Apply for SSB?
You may apply for SSB online via DBS, OCBC, or UOB internet banking. We have written a comprehensive guide on how to buy SSB. You may follow our guide to apply and check your SSB holdings afterward.
How to Redeem SSB?
You can redeem your SSB at any month without penalty and still earn the accrued interest up to the time of redemption. You have to pay a $2 transaction fee. If you want to redeem your SSB, you can do so online via DBS, OCBC, or UOB internet banking. We have written a comprehensive guide on how to redeem SSB with detailed step-by-step instructions and screenshots.