
The auction for T-bill BS24104T has concluded with a cut-off yield of 3.8%. Fantastic news for investors! This yield is a significant jump from the previous auction’s yield of 3.66%. Let’s dive into the auction result.
Auction Results
Here is the summary for the T-bill BS24104T auction:

Yield Rebounded
Investors should be satisfied with the result of this T-bill BS24104T auction. The cut-off yield rebounded strongly to 3.8%, way above the 3.7% level we saw throughout late 2023. Let’s see where we are historically:

The historical chart above shows that we are returning to the range we have been hovering in throughout 2023. Looking further back, we can also see that the current yield is among the highest in recent history.
Lower Demand
The T-bill BS24104T auction saw demand drop from $13.5 billion to $12.4 billion. That is a $1.1 billion drop!
While the non-competitive bid increased from $2.0 billion to $2.4 billion, the competitive bid amount fell significantly, contributing to the drop in demand.
The good news is that non-competitive bids were still below the allocation limit, so all non-competitive bidders received their full allocation. Congratulations!
Lower demand could be one factor driving the higher yield here.
T-Bill Alternatives
T-bills, currently yielding 3.8%, have become a more attractive fixed-income investment choice compared to other options that offer lower returns. Let’s see some of these alternatives.
Fixed Deposits
All fixed deposits in Singapore offer lower rates than 3.8%. As of this writing, the highest 6-month fixed deposit rate is 3.5%, offered by CIMB Bank. If you are their preferred banking client, you can get up to 3.55%. The rates for local banks, such as DBS, OCBC, and UOB, are even lower, ranging between 2.9% and 3.0%.
Because these fixed deposit rates are much lower than what T-bills can offer, it is safe to say that T-bills are currently the more competitive option.
If you want to compare fixed deposit rates offered by various banks in Singapore, you may refer to our coverage of the best fixed deposit rates in Singapore.
Cash Management Accounts
Some cash management accounts offer guaranteed principal and interest payout. They are similar to T-bills and fixed deposits. The two, in particular, are Syfe Cash+ Guaranteed and StashAway Simple Guaranteed. Both offer 3.6% for their 6-month lock-up period as of the time of this writing. Again, unfortunately, this 3.6% is much lower than what T-bills can offer.
Some other cash management accounts can offer higher rates than T-bills but have a higher risk profile, i.e., your principal and interest payouts are not guaranteed. You can weigh the risk vs. return for these cash management accounts to see if they fit your investing objectives.
High-Yield Savings Accounts
Another popular option for parking short-term cash is a high-yield savings account, which offers a competitive yield if you meet specific criteria, such as crediting your salary, spending on a credit card, or buying insurance.
One thing to note is that these high-yield savings accounts offer floating interest rates, meaning they follow prevailing interest rate movements. Unlike T-bills and fixed deposits, which lock rates for the full term, these rates will rise and fall almost immediately with interest rate fluctuations.
Given the anticipated reversal of interest rates this year, these higher floating rates may only last for a while longer. Therefore, there may be better options than these savings accounts if you believe the rates are about to reverse soon.
What Would We Do?
We have used, and will continue to use, T-bills to park our short-term cash. Yields have become quite competitive again, especially with the rebound in the latest T-bill BS24104T auction.
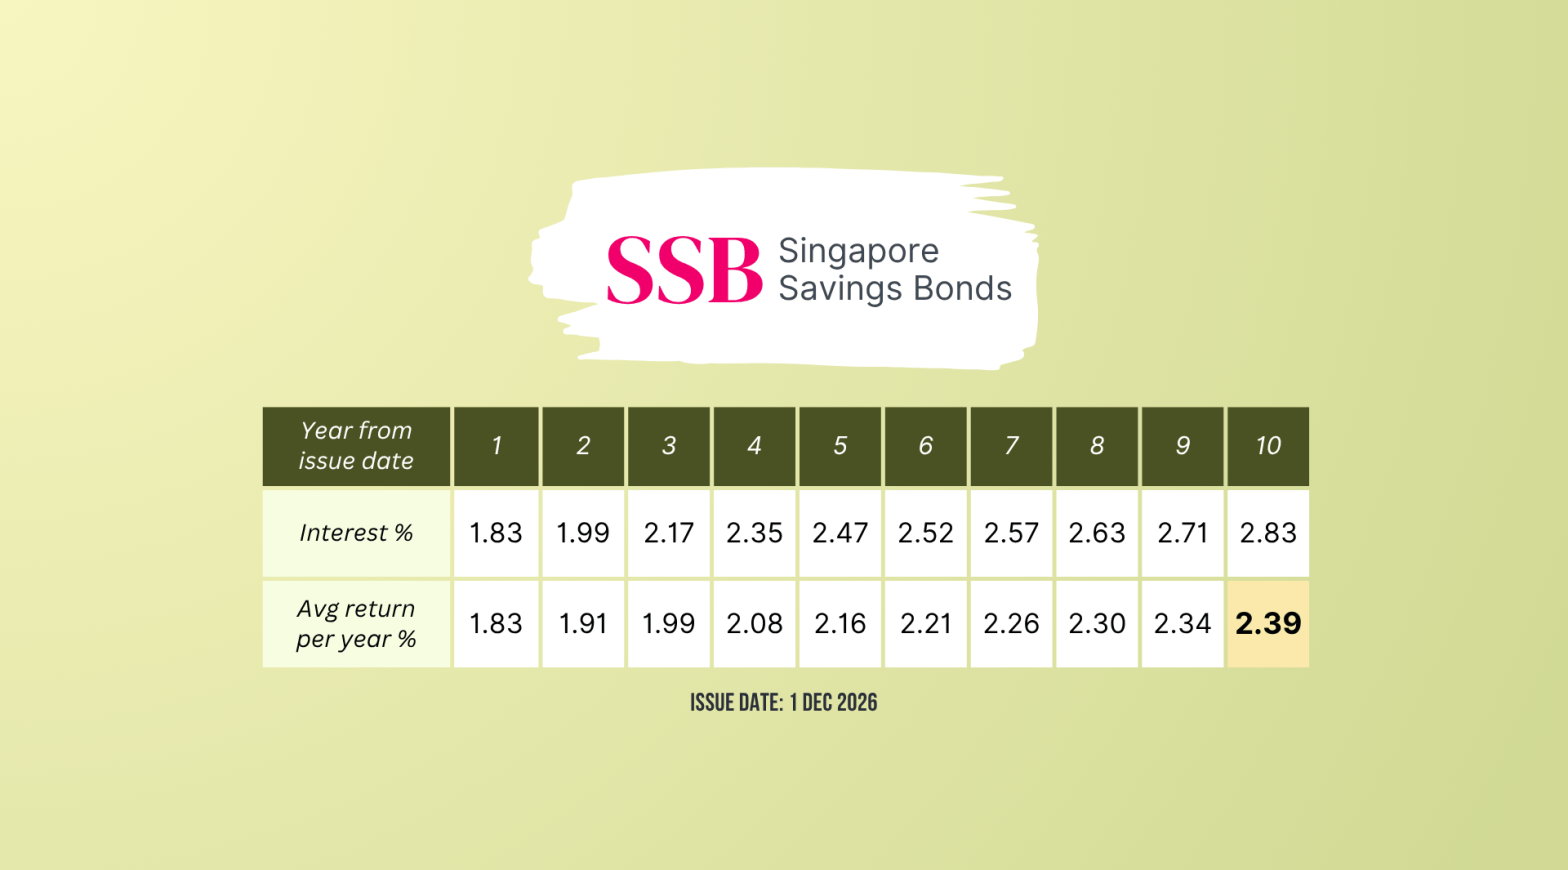
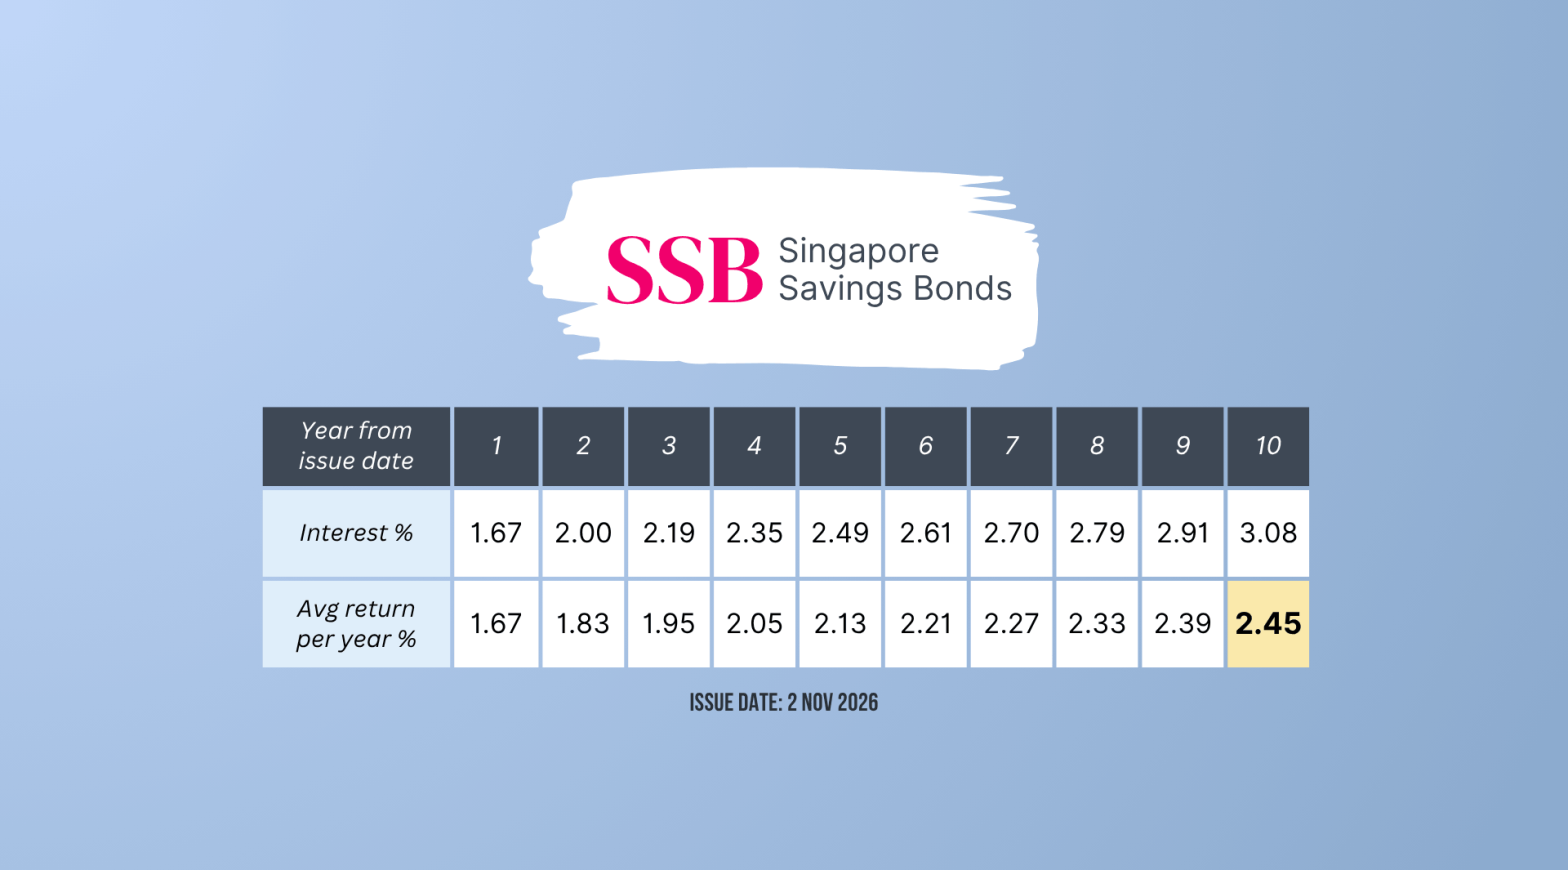
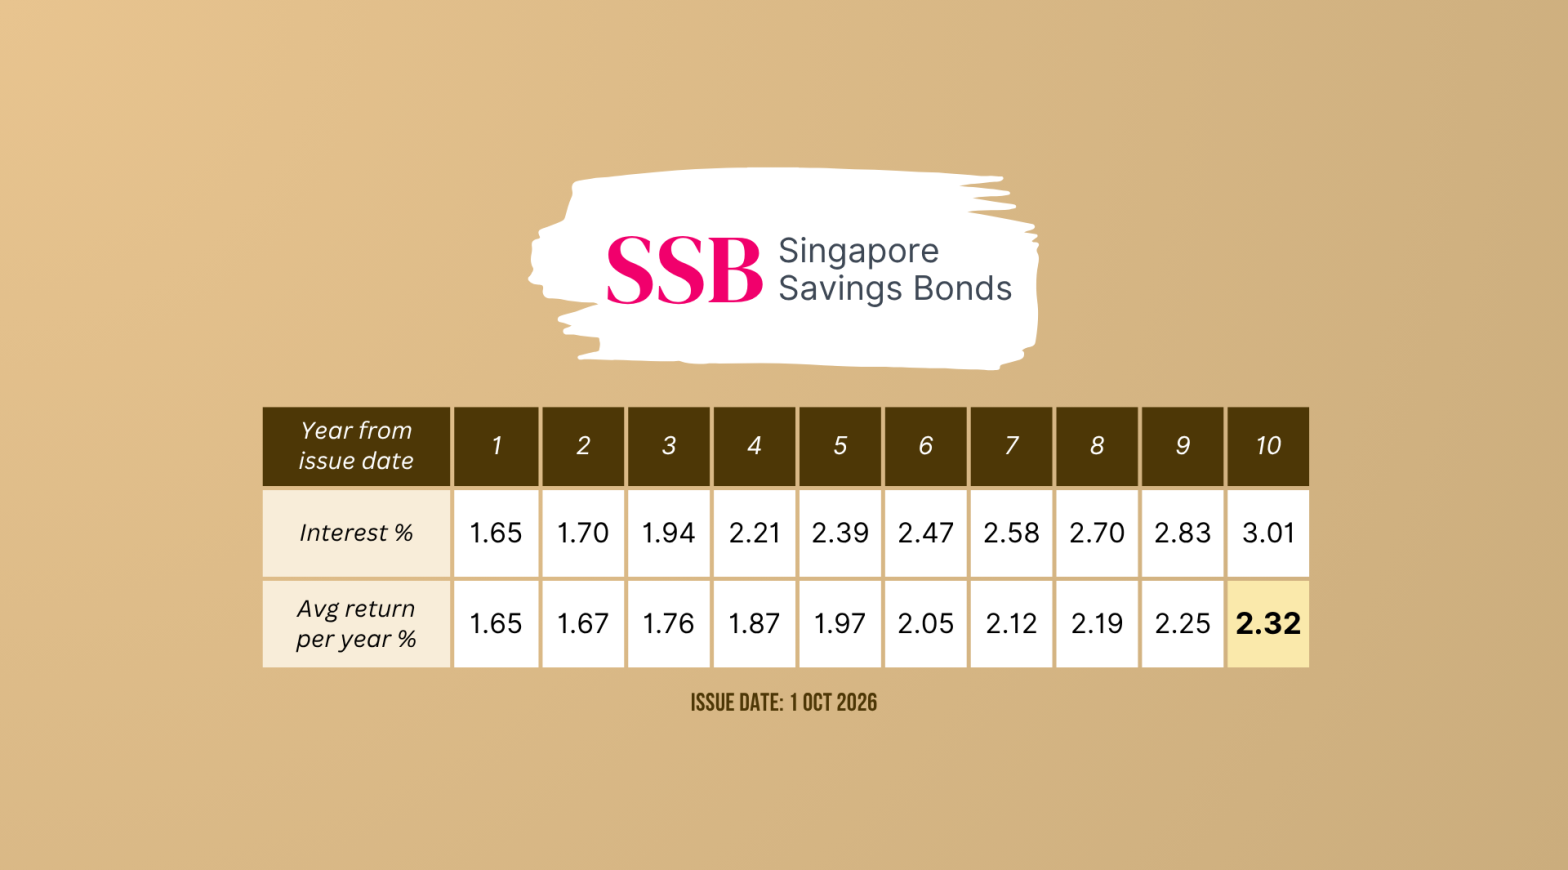
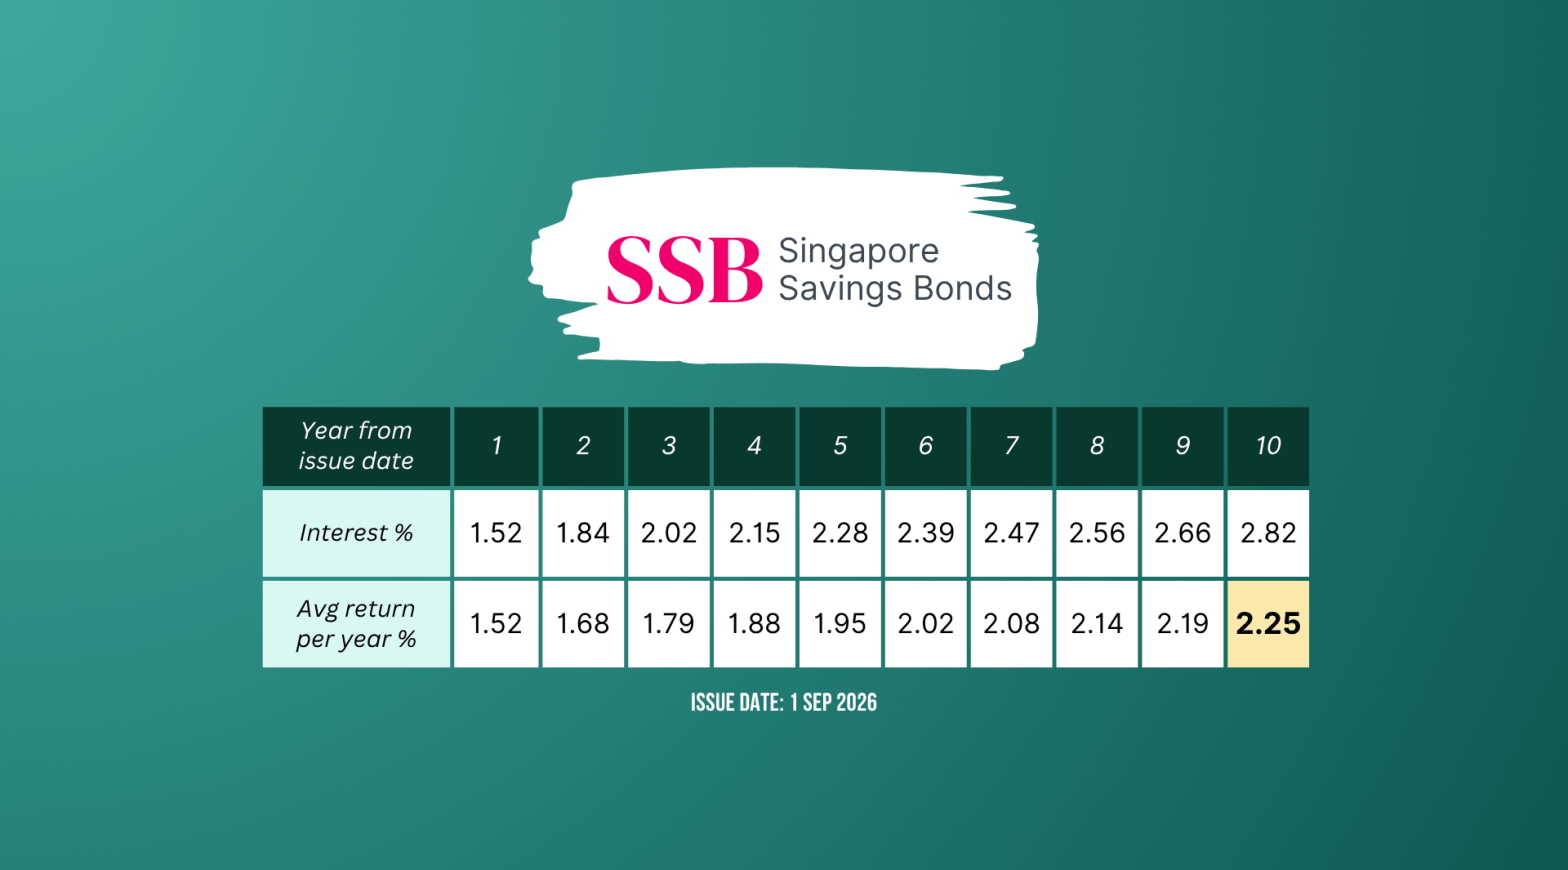
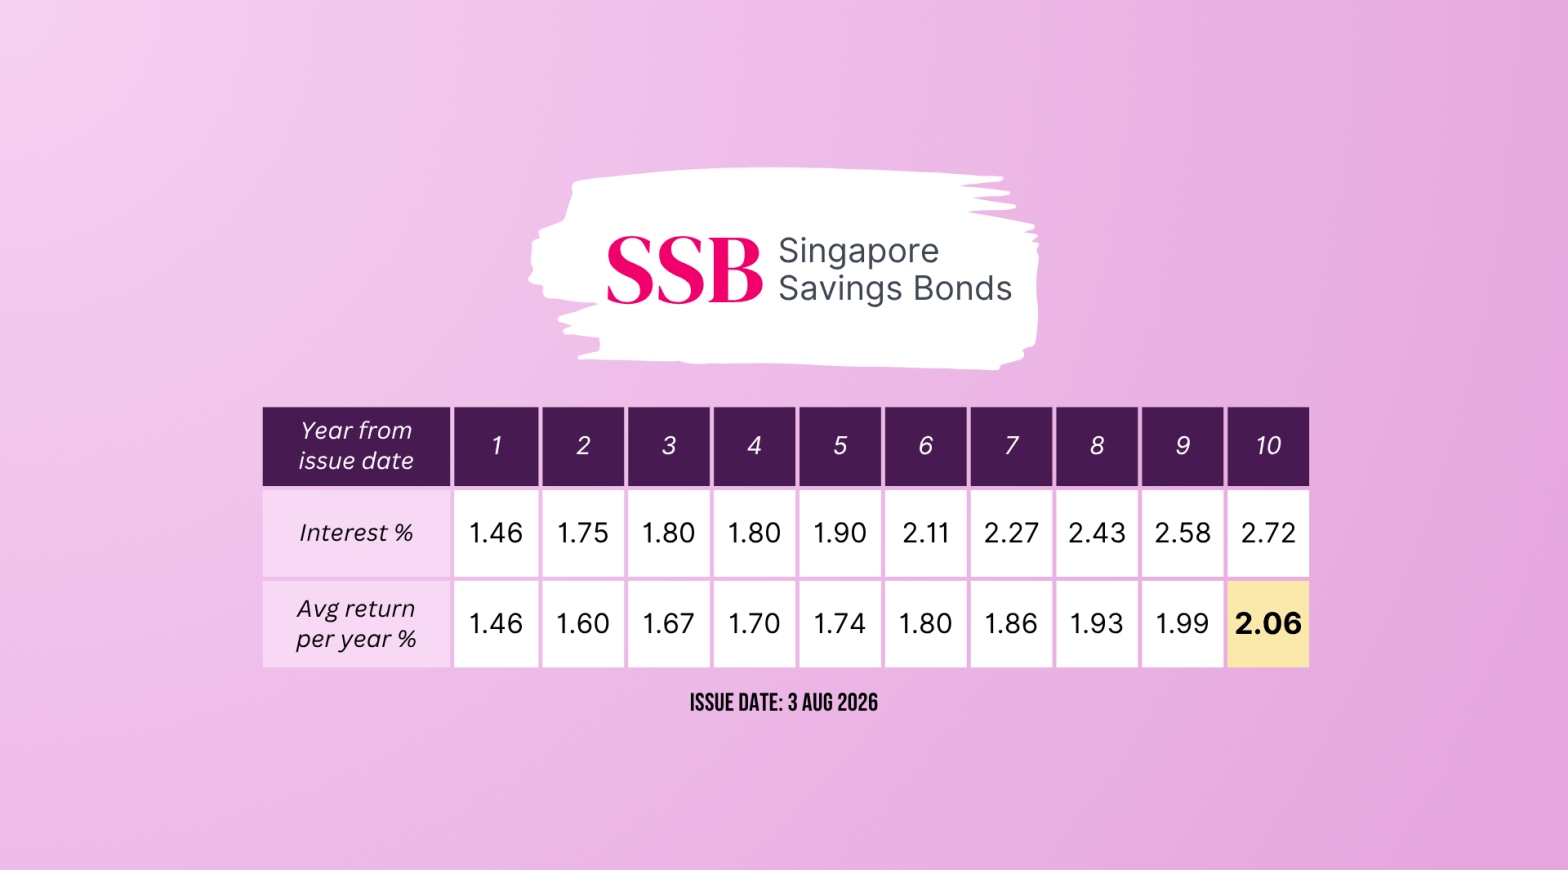
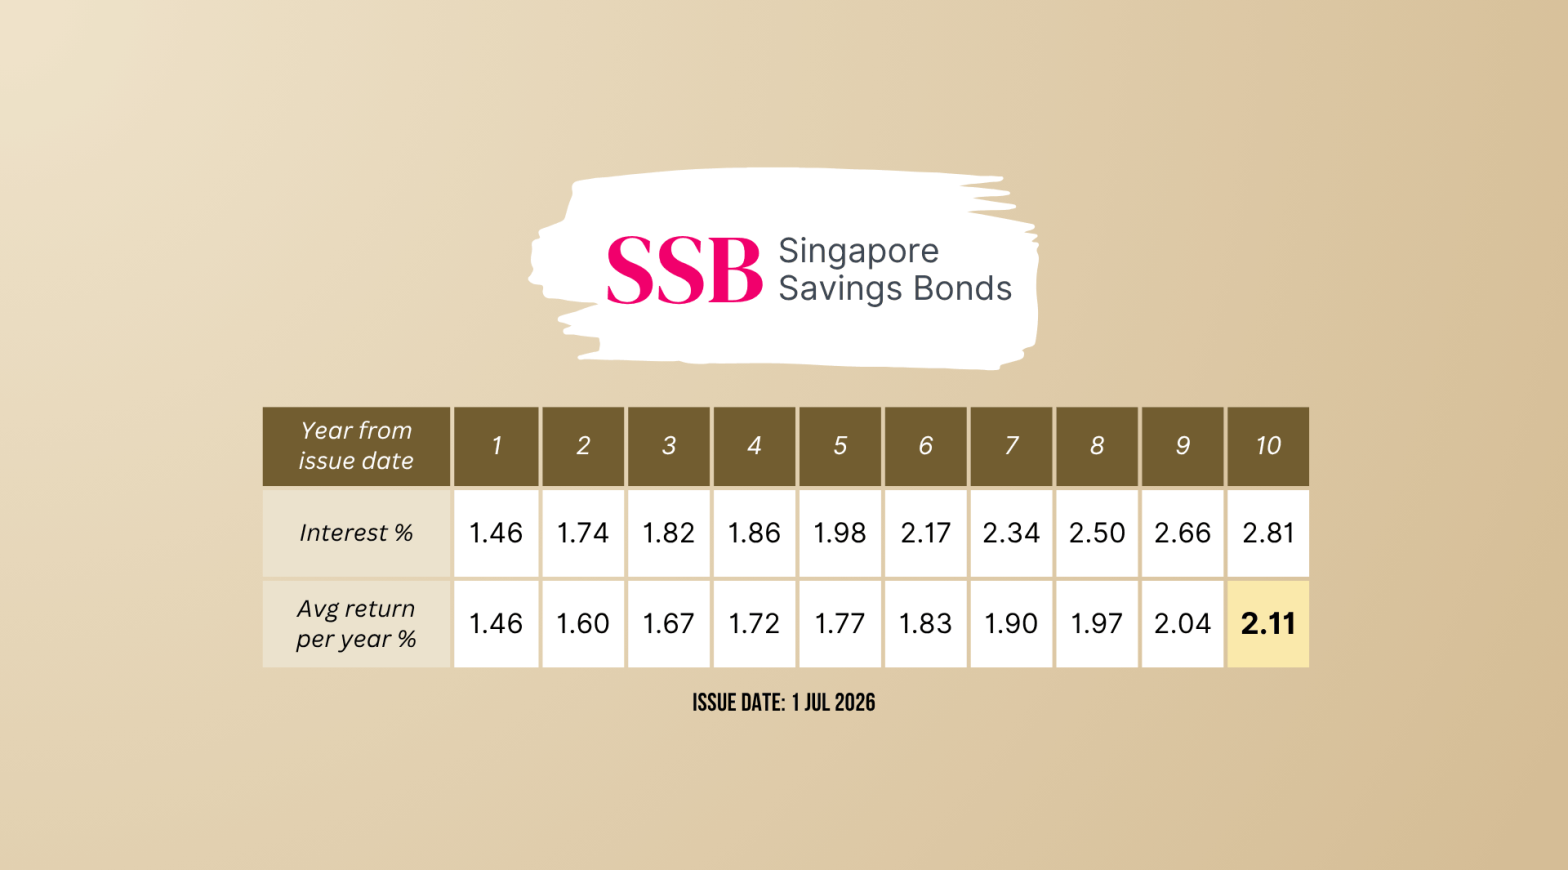
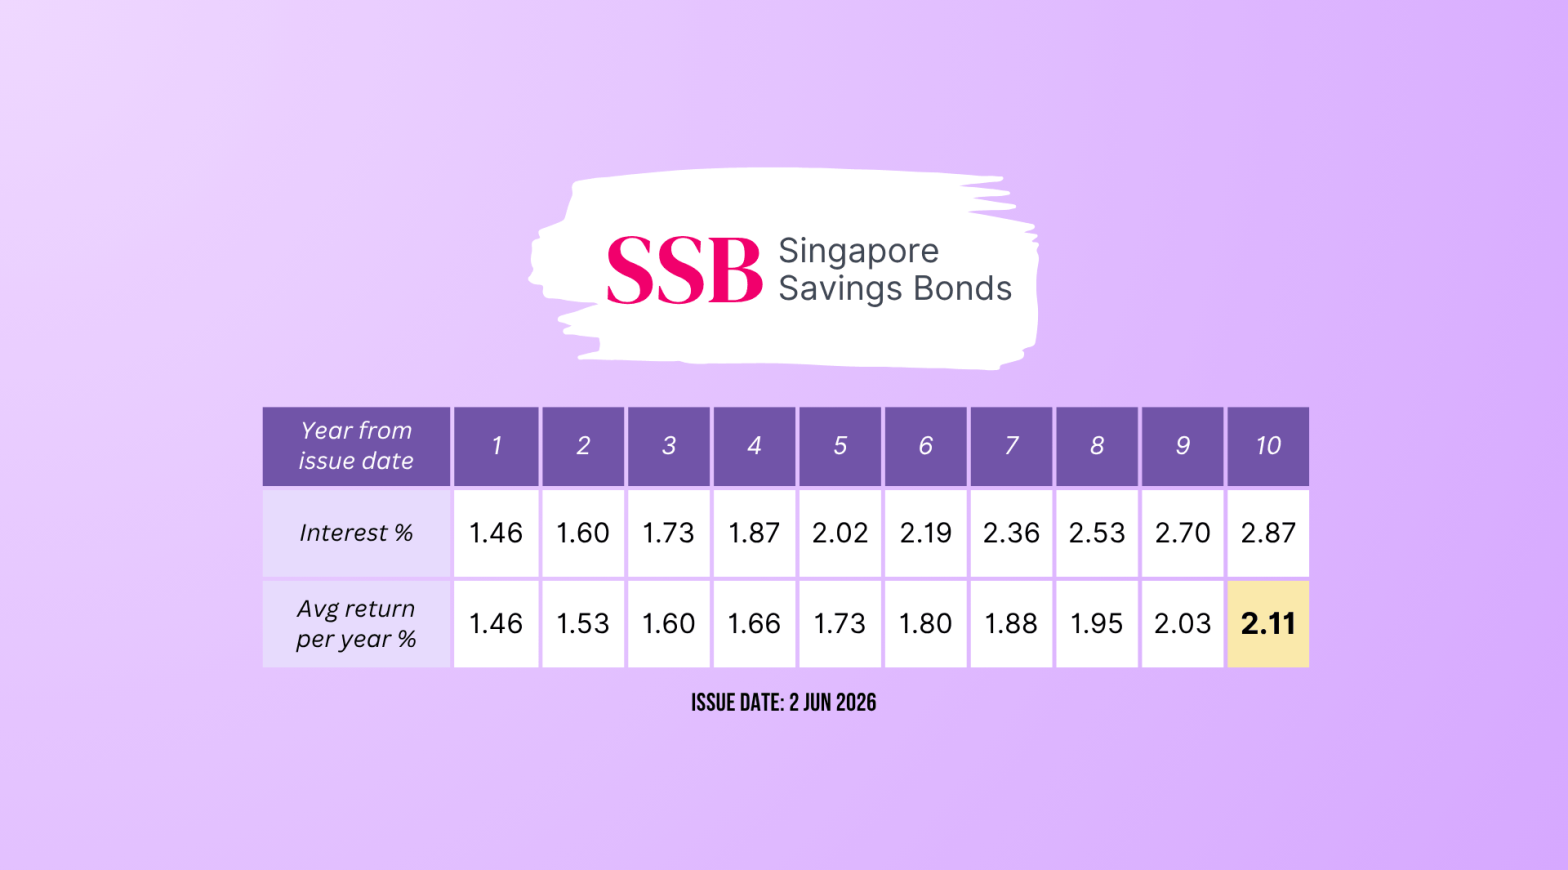
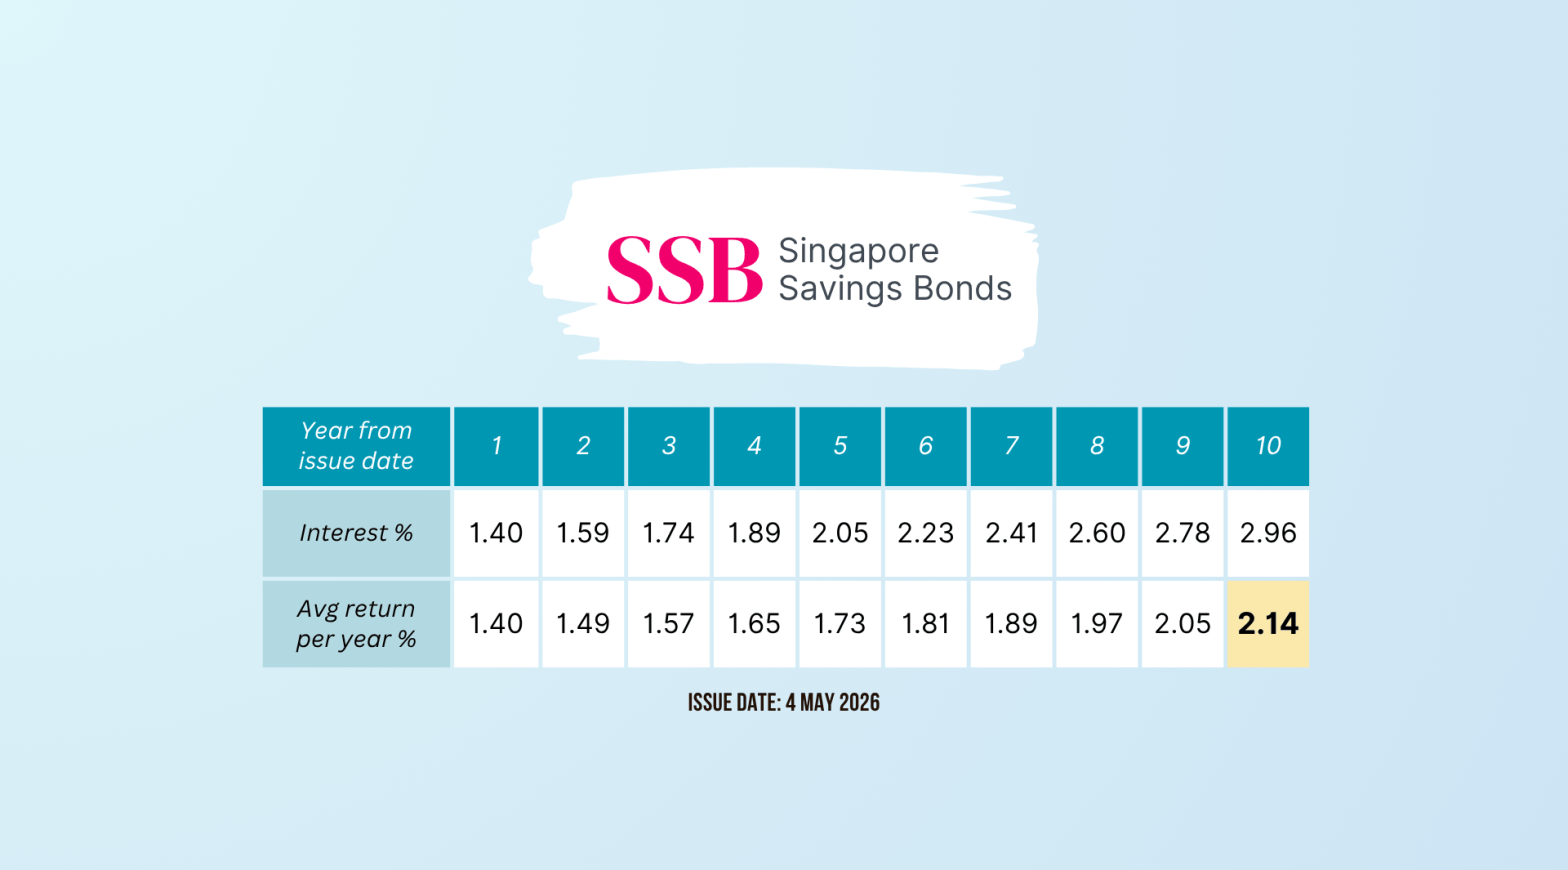
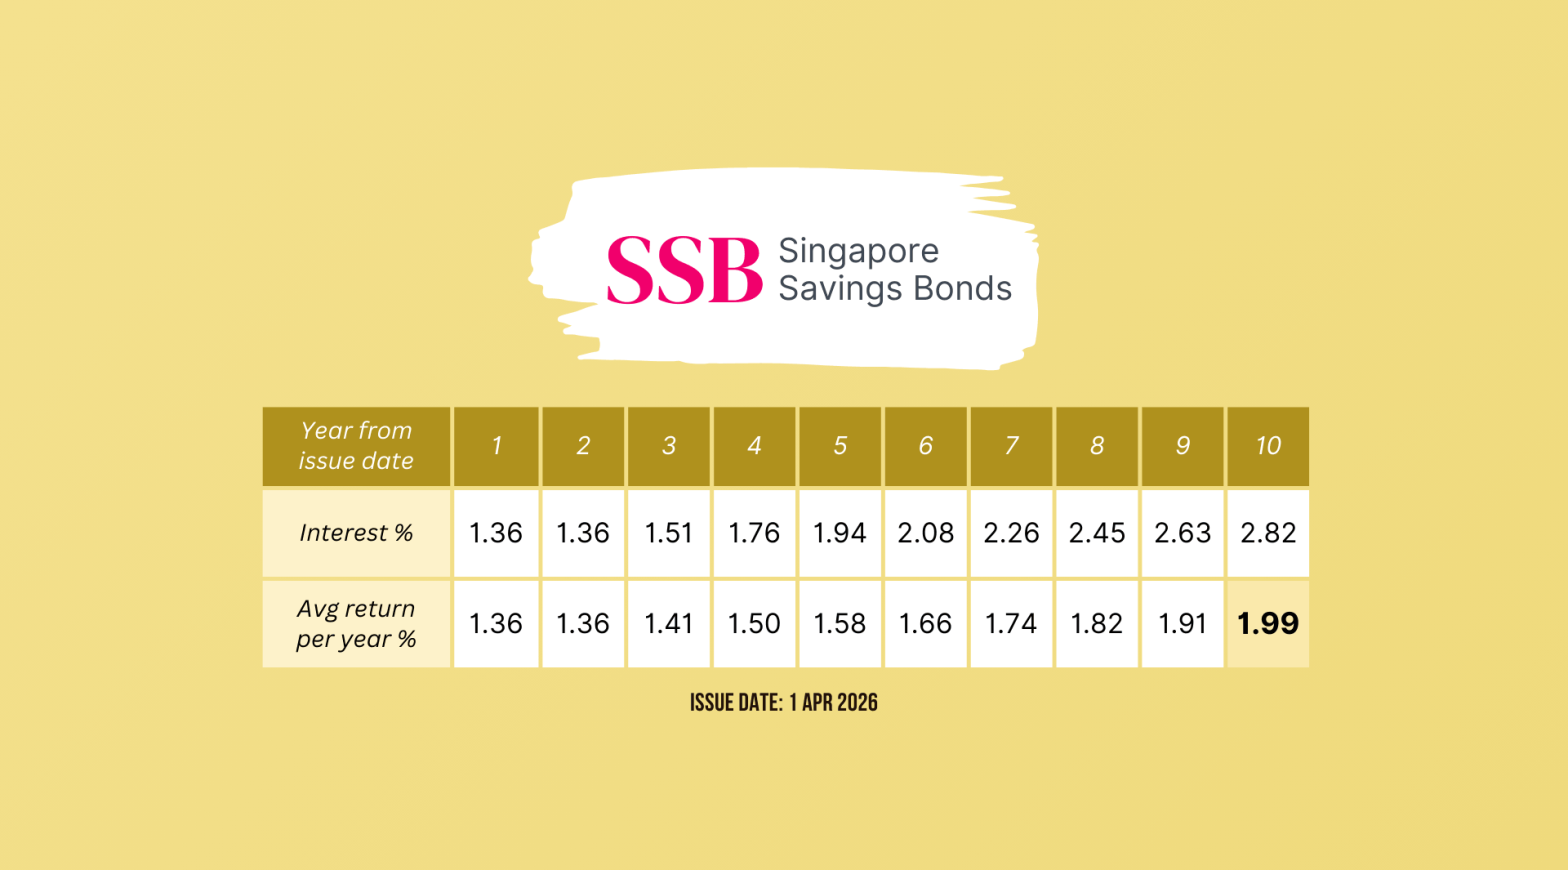
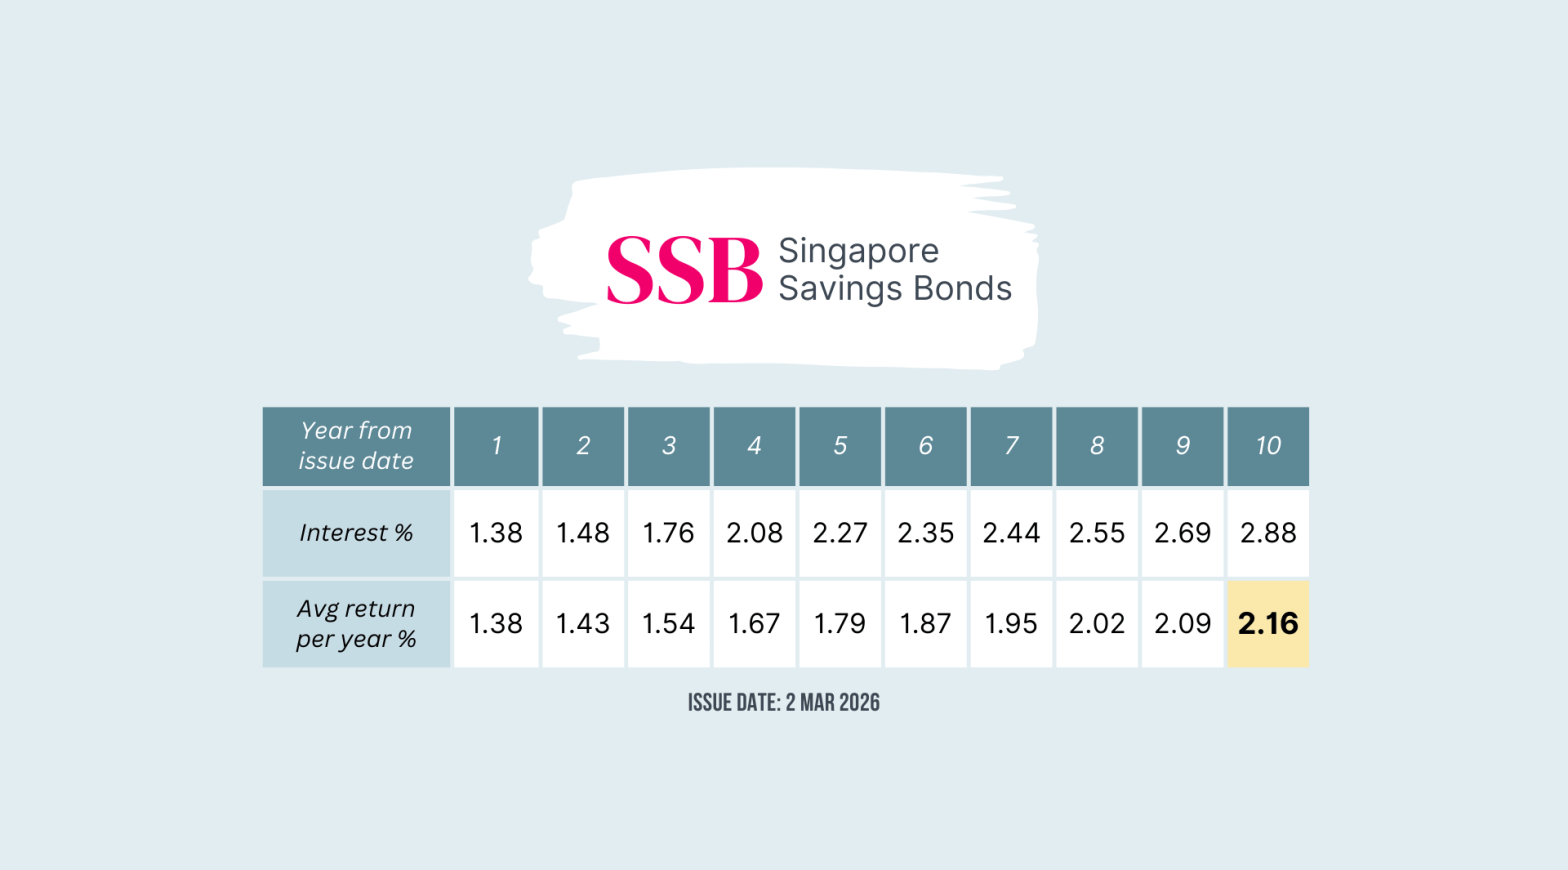
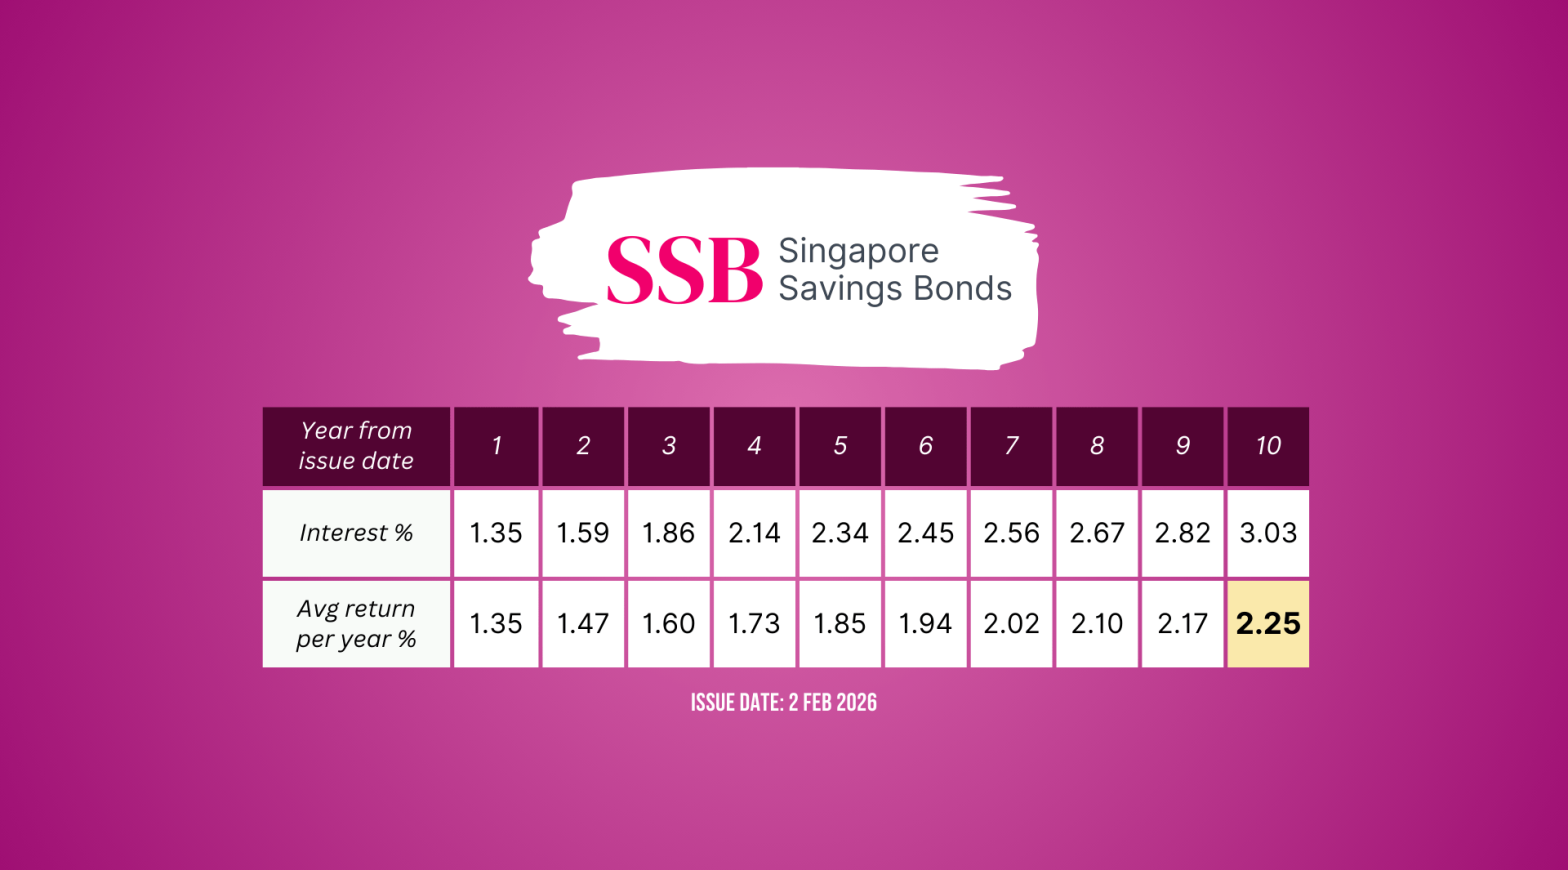
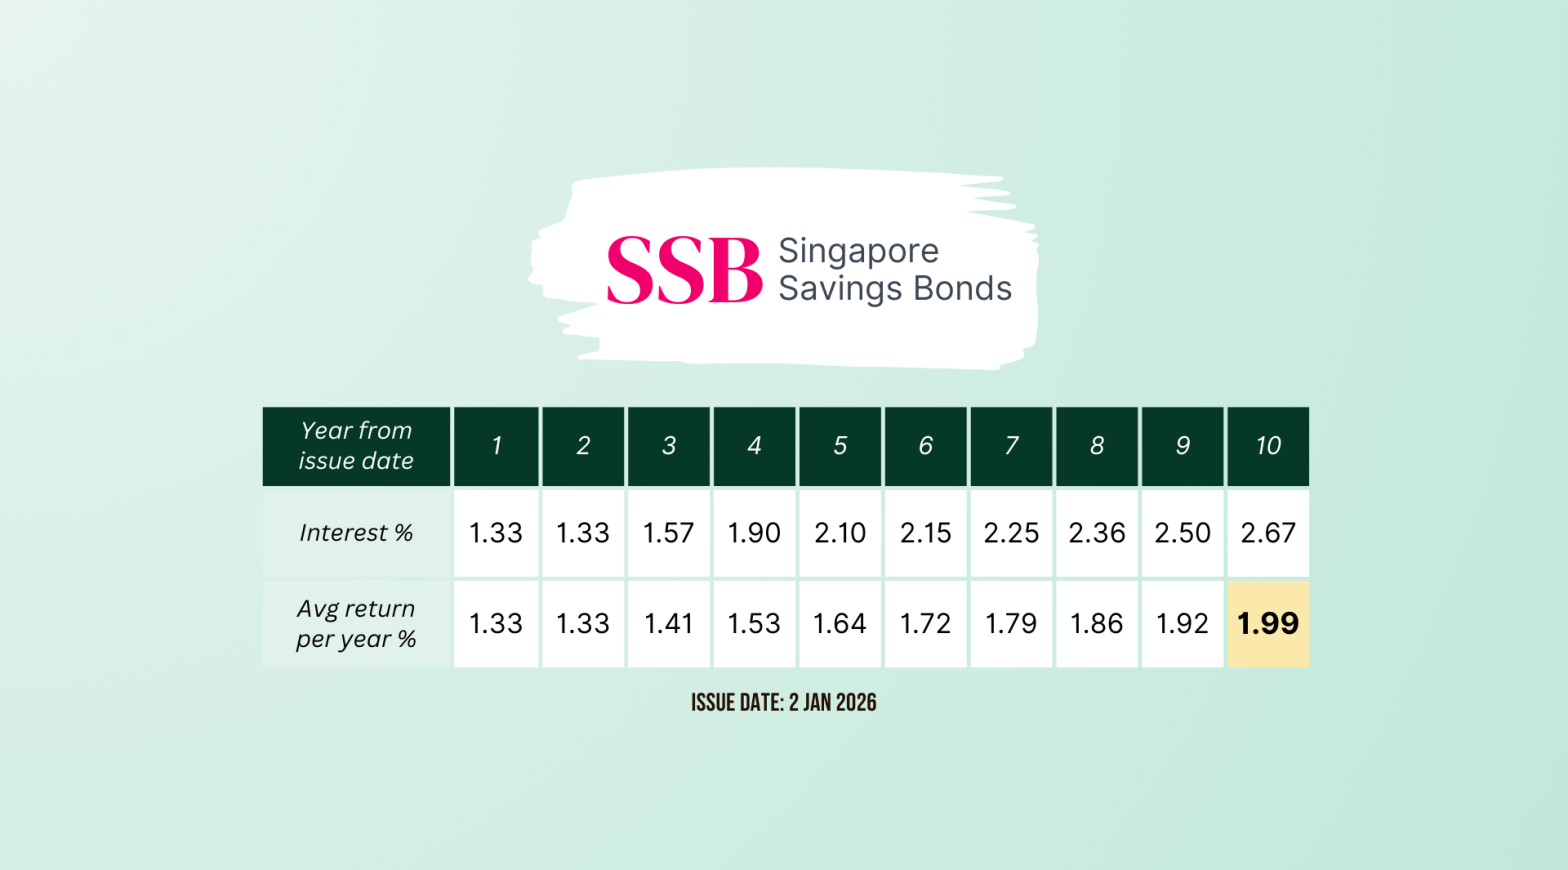
With interest rates expected to decline this year, we have moved some of our short-term cash into Singapore Savings Bonds (SSB) to lock in higher rates for longer. Although SSB is a long-term 10-year bond, you can redeem it monthly without penalty while still earning accrued interest. Perfect for parking short-term cash!
Did you get your T-bills allocation in this auction?
If you are interested in applying for the next T-bill auction, you may follow our guide on how to buy T-bills.
If you plan to apply with CPF, you can estimate the additional interest you may earn using our CPF T-bill calculator.