
The auction for the 1-year T-bill BY24100T resulted in a cut-off yield of 3.45%. That is a significant drop from the previous auction, which yielded 3.7%. Ouch! The result may disappoint some investors who expected a more competitive yield before the interest rate reversal that may start to happen this year. What caused the drop, and is the current yield still competitive enough?
Auction Result Summary
Allotment Result
| Total Amount Allotted | S$4.5 billion |
| Amount Allotted to Non-Competitive Applications | S$1.8 billion |
| Total Amount Applied | S$14.4 billion |
| % of Competitive Applications at Cut-off Allotted | Approximately 17% |
| % of Non-Competitive Applications Allotted | 100% |
| Bid-to-Cover Ratio | 3.19 |
Yield and Price
| Cut-off Yield | 3.45% p.a. |
| Cut-off Price | 96.559 |
| Median Yield | 3.4% p.a. |
| Median Price | 96.609 |
| Average Yield | 3.13% p.a. |
| Average Price | 96.879 |
Yield Dropped
T-bill BY24100T auction resulted in a cut-off yield of only 3.45%. With such a significant drop from the previous auction, it is understandable that many investors were left disappointed. But is it really that bad? We may need to zoom out to see where we are historically and see if the current yield is still competitive enough.

From the historical chart above, we can see that the current yield, though lower, is still among the highest in recent years.
The Fed and the market also expect interest rates to start reversing this year, so it is understandable that this 1-year T-bill yields less than the 6-month T-bill. For reference, the latest 6-month T-bill yielded 3.7%.
Demand Jumped
We saw a significant jump in total applications in this T-bill BY24100T auction. The total application amount was $14.4 billion, much higher than the $11.9 billion we saw in the previous auction.
The higher demand likely reflects CPF applicants, who usually prefer longer-duration T-bills to reduce the opportunity cost of investing CPF money. We may also see the impact of expectations of an interest rate reversal here, with many investors flocking to this 1-year T-bill (BY24100T) to lock in higher rates for longer.
The jump in demand may be a main contributor to the drop in the cut-off yield.
Non-Competitive Bids
Good news to non-competitive bidders: you got full allocation, yay! Because most of the application demand came from competitive bidders, there were enough allocations for all non-competitive bidders in this auction. Congratulations!
How Competitive Is This Yield Compared to Alternatives?
As many investors may have failed to secure an allocation or were disappointed with this T-bill BY24100T auction result, let us look into some alternatives for this 1-year T-bill.
Fixed Deposits
The most popular alternative is the 12-month fixed deposits. As of this writing, the highest 12-month fixed deposit rate is 3.2%, offered by the Bank of China and DBS. If you prefer local banks, DBS offers 3.2%, but only up to $19,999. If you want to invest more, consider UOB’s 3.1% offer.
Fixed deposits, unfortunately, do not offer competitive rates to match the latest 1-year T-bill cut-off yield of 3.45%.
Regardless, if you want to apply for fixed deposits, you can refer to our Singapore fixed deposit rates page.
6-Month T-Bills
Investors may also explore the 6-month T-bills as an alternative. They are shorter in duration but offer a higher yield. The latest cut-off yield for the 6-month T-bill was 3.70%.
With 6-month T-bills, please note that you will face refinancing risk when your T-bills mature in six months. You will need to apply for another T-bill again with the prevailing interest rates at the time of application. Given the anticipated shift in interest rates this year, you may not be able to secure a similar yield in six months.
You may refer to our Singapore T-bills interest rates page to see the historical yield movement of the 6-month T-bills.
Syfe Cash+ Guaranteed
Syfe Cash+ Guaranteed offers 3.5% for a 12-month lock-in period. This is higher than the cut-off yield in the latest 1-year T-bill. If you are interested in this offering by Syfe, please refer to our list of Singapore cash management accounts to learn more.
Please note that although it behaves very similarly to fixed deposits, with guaranteed principal and interest, Syfe Cash+ Guaranteed is considered an investment and, therefore, not subject to SDIC insurance.
What Would We Do?
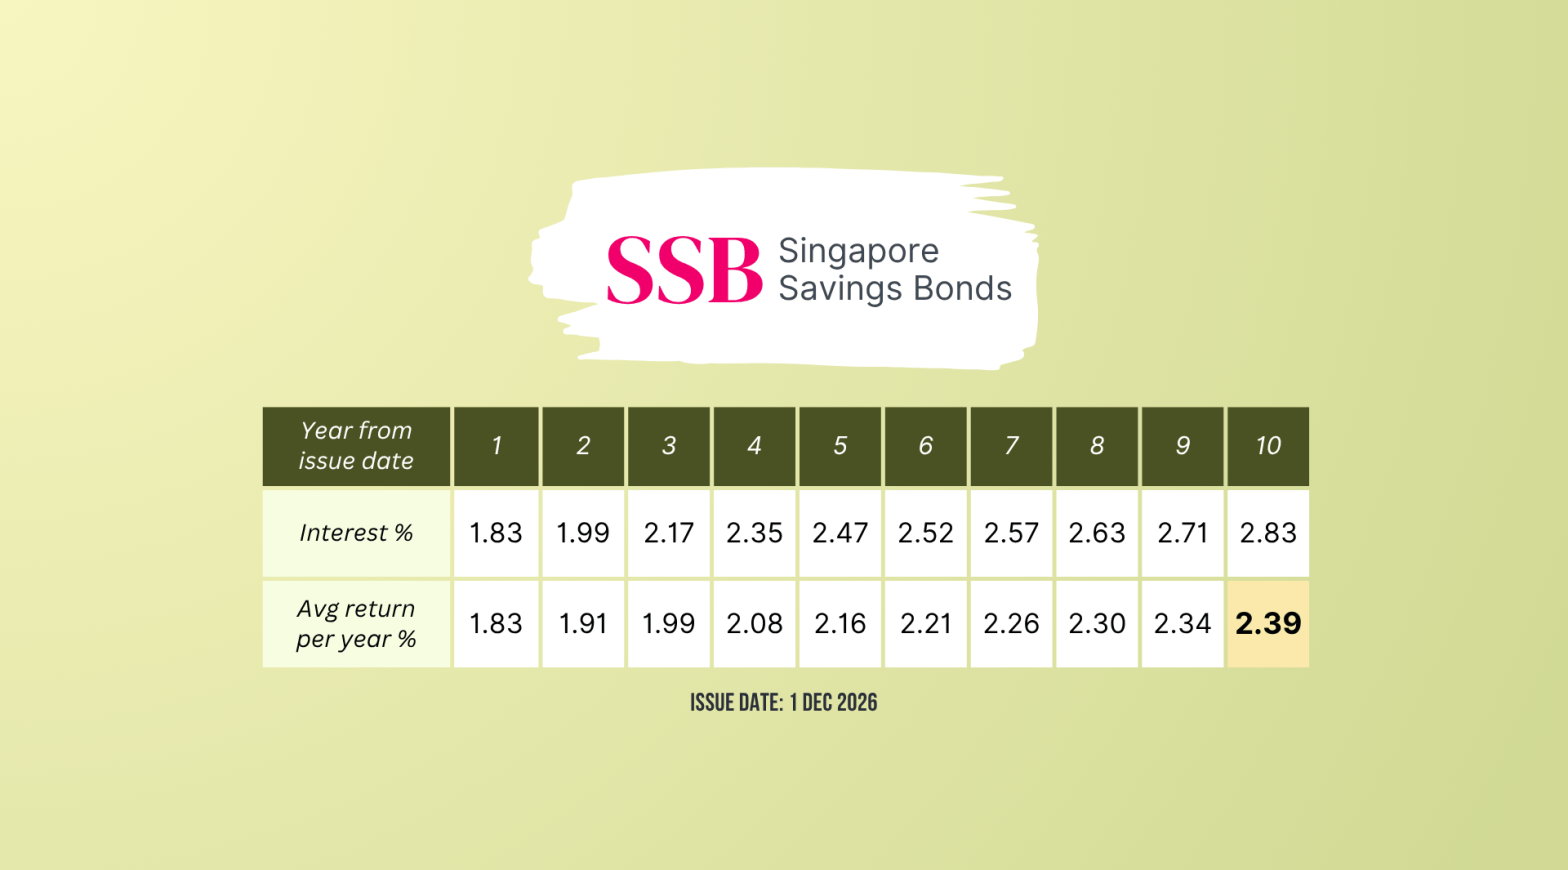
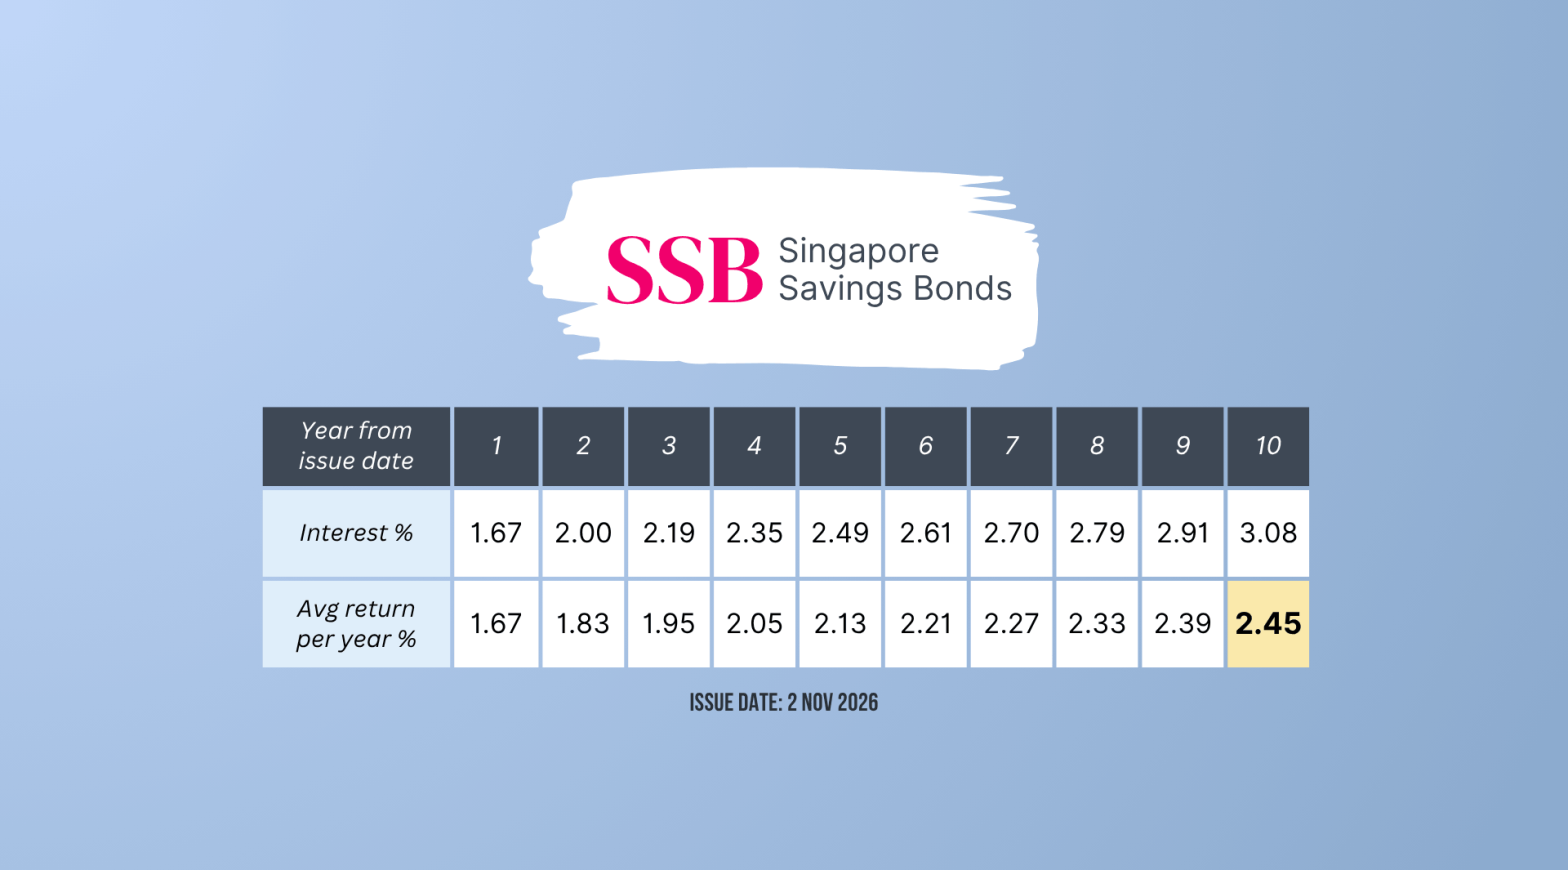
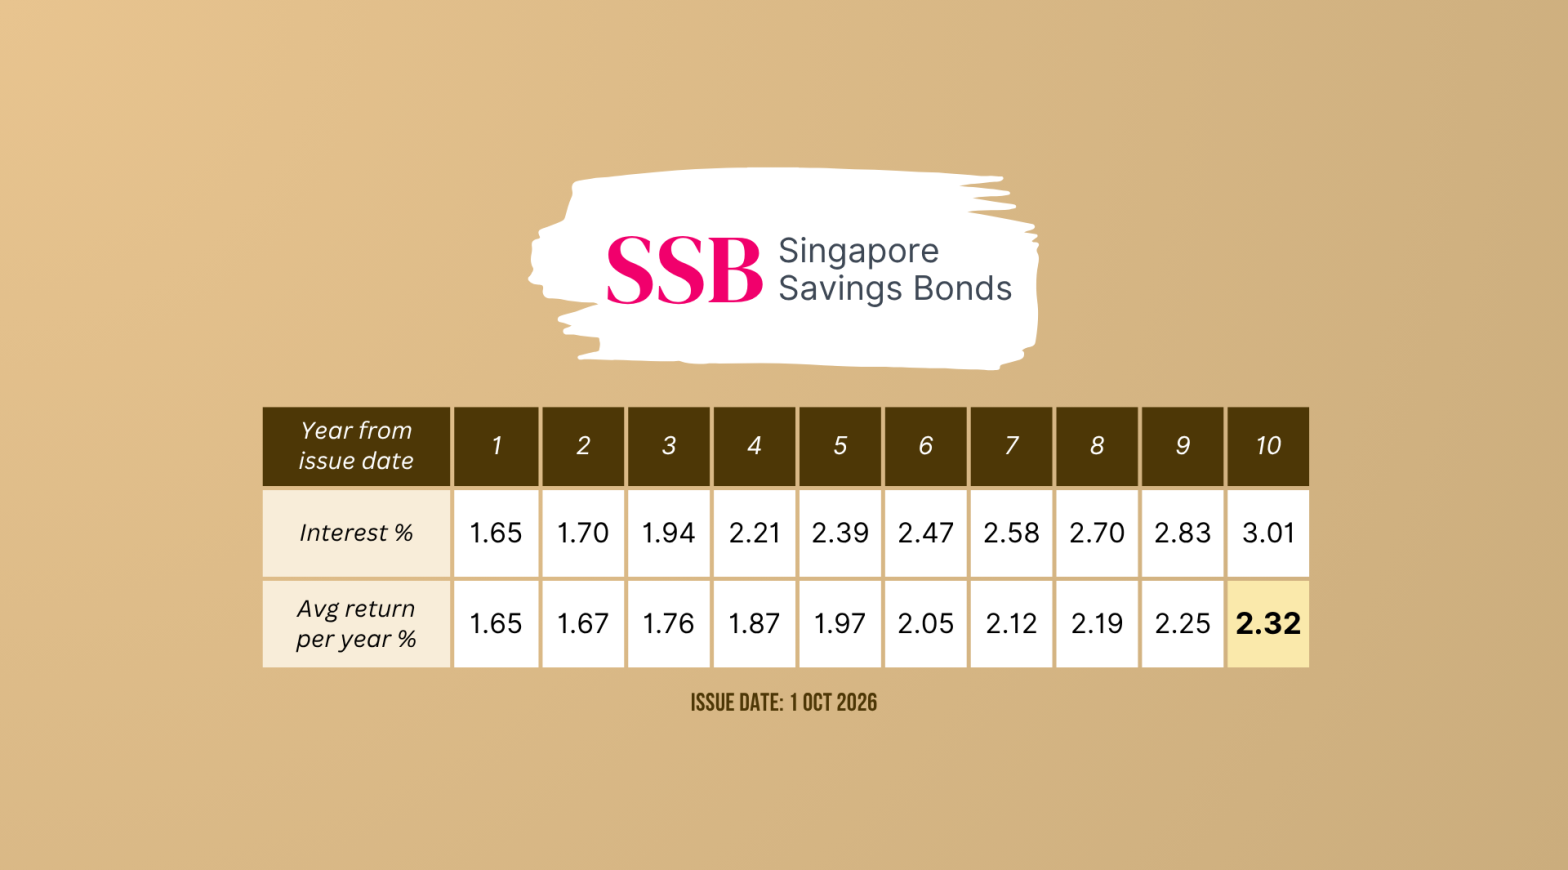
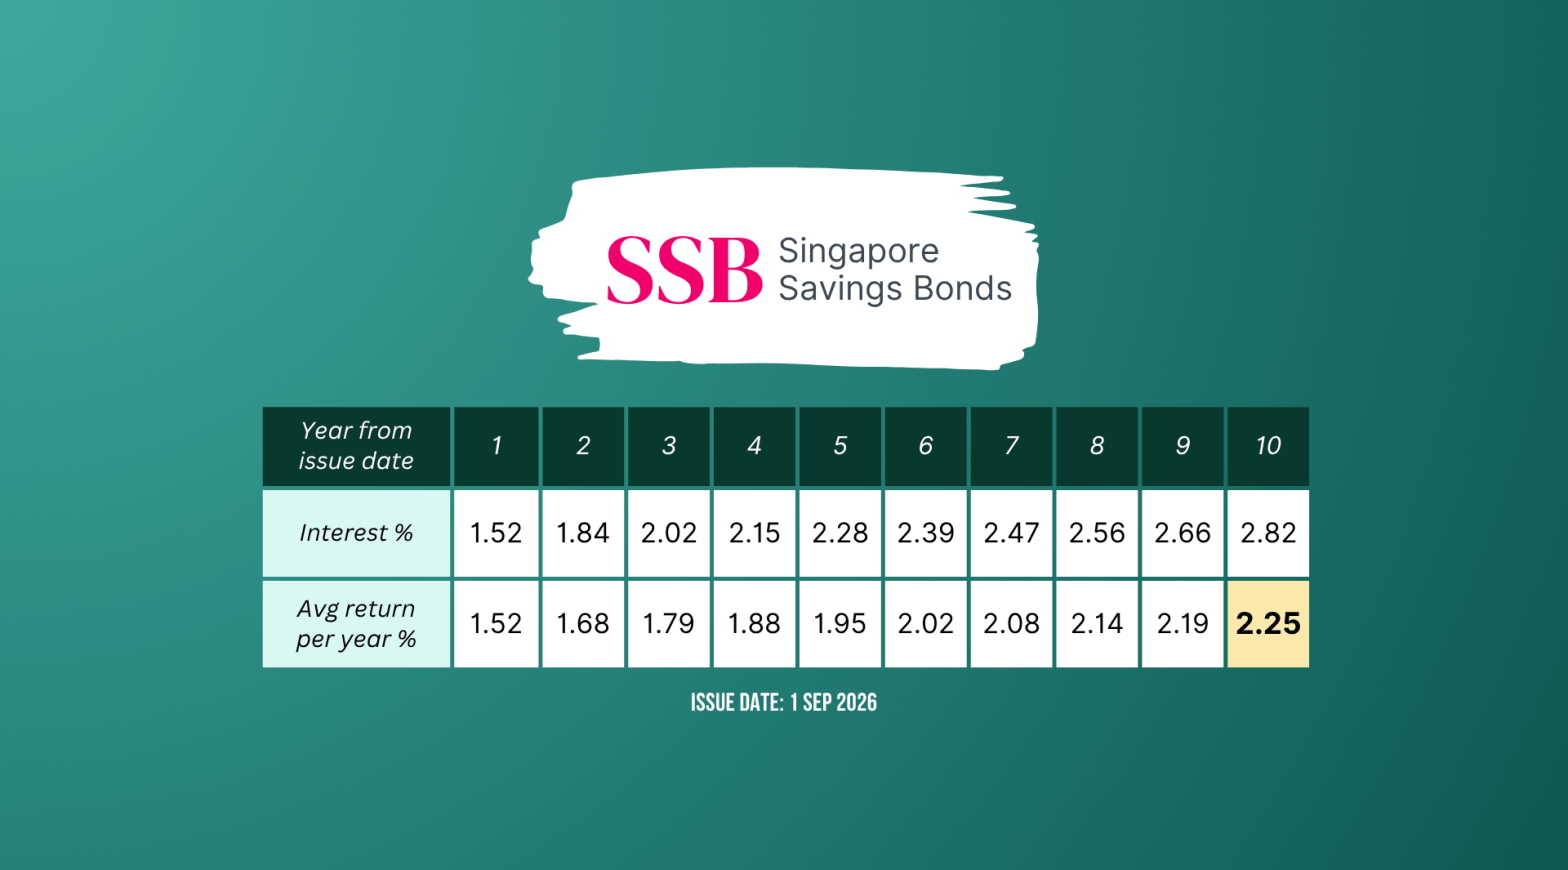
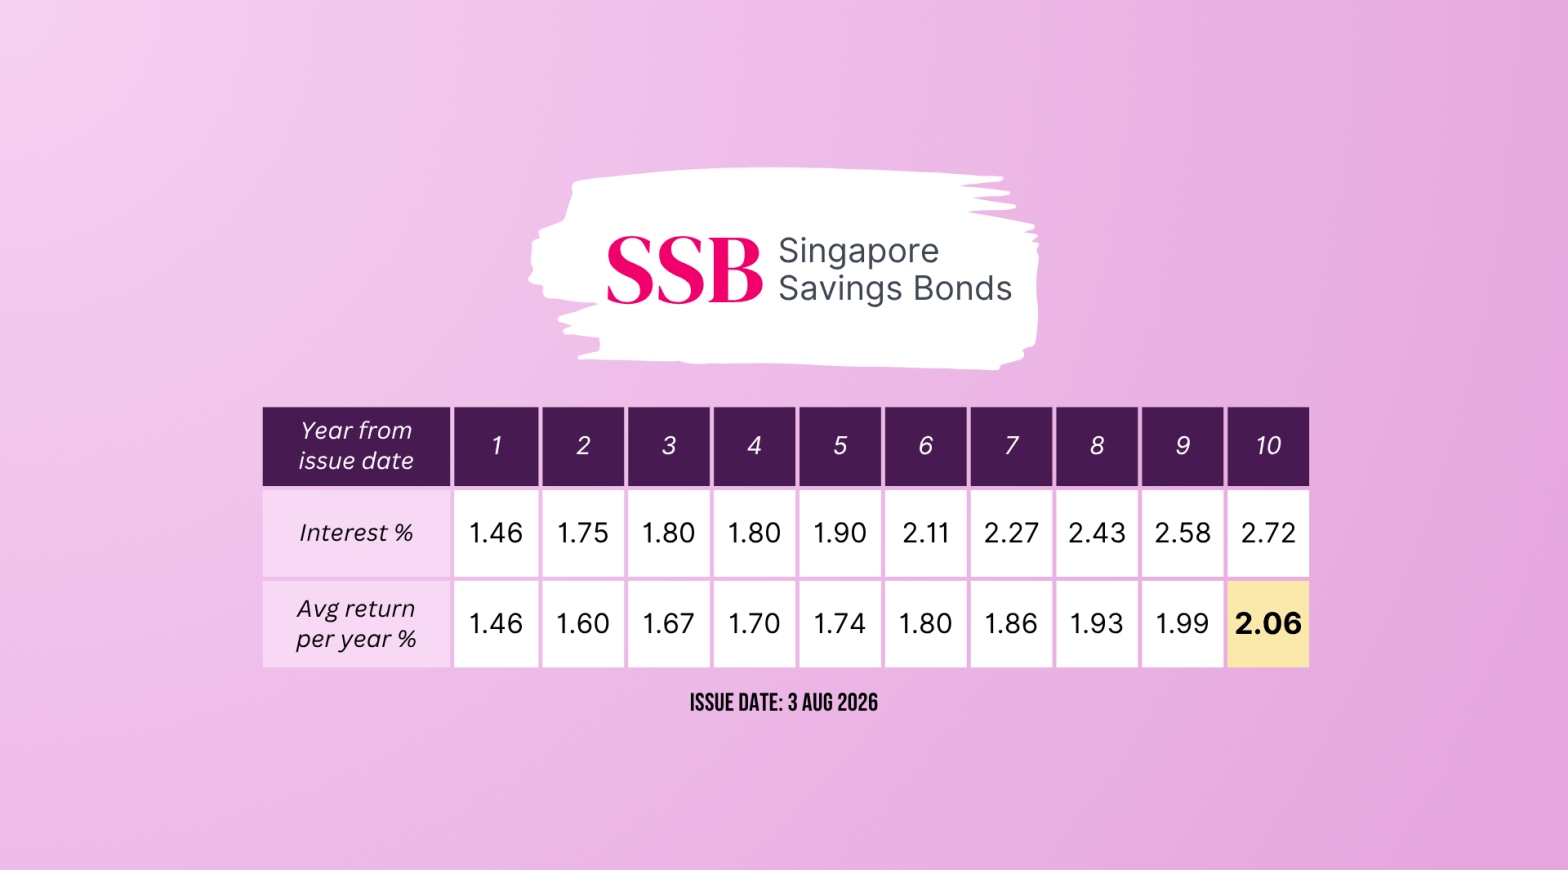
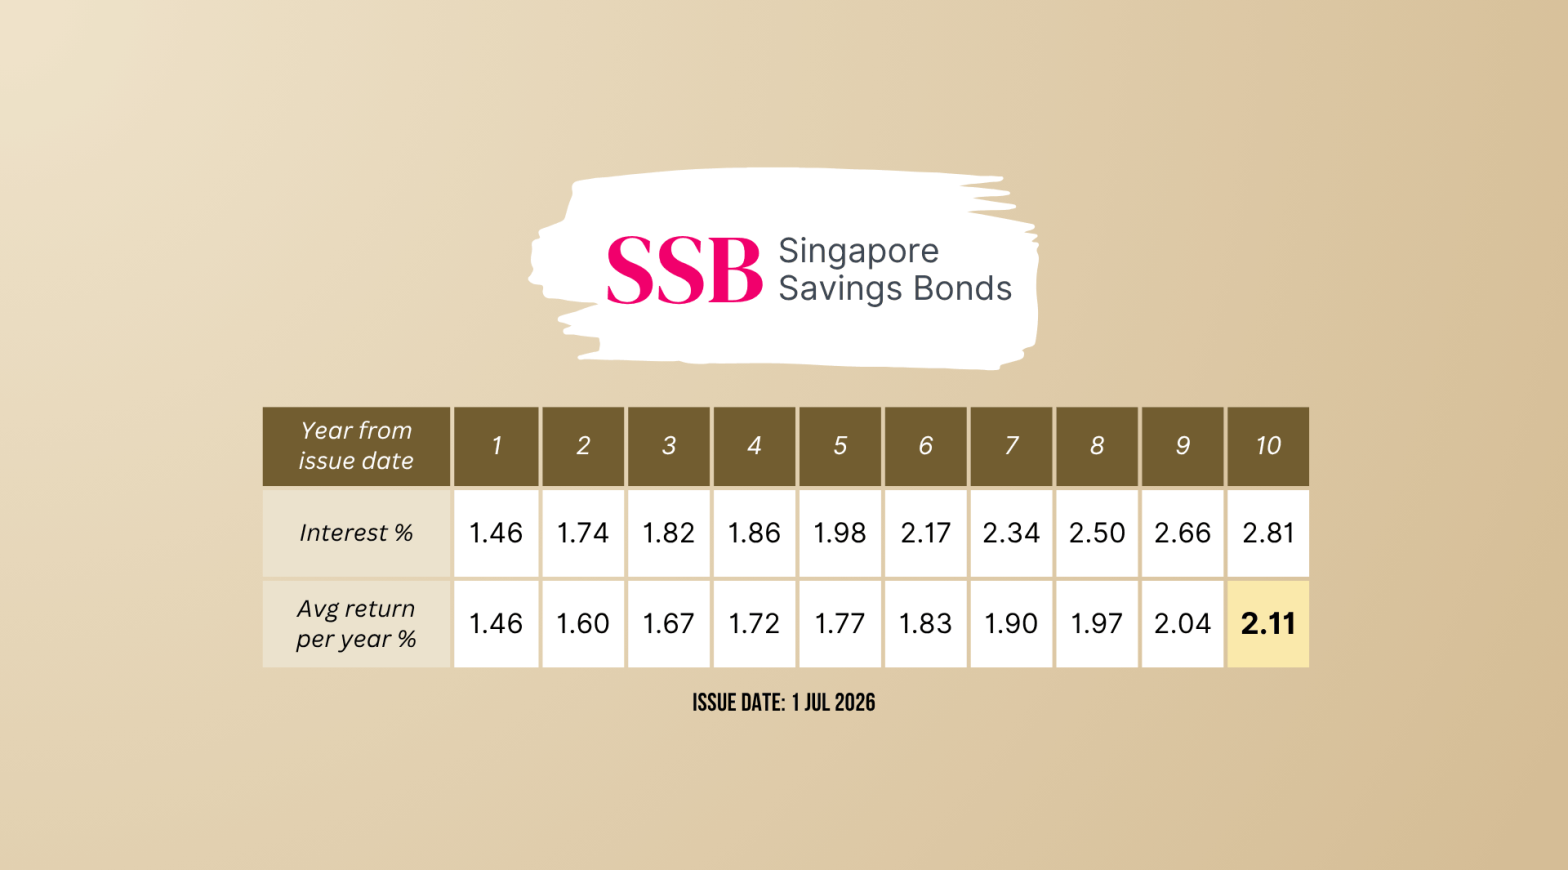
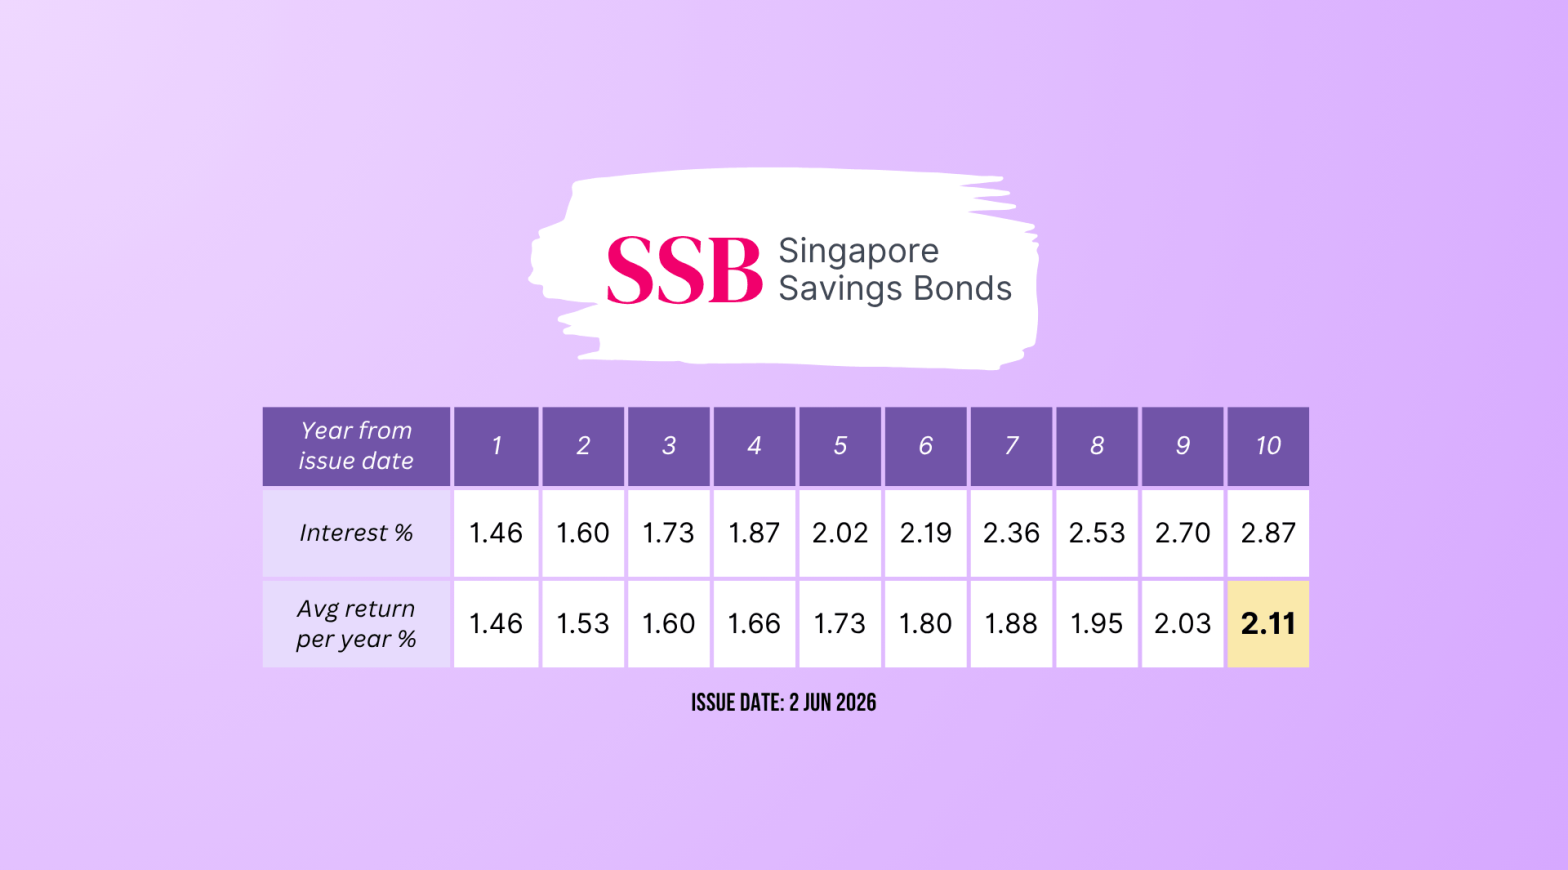
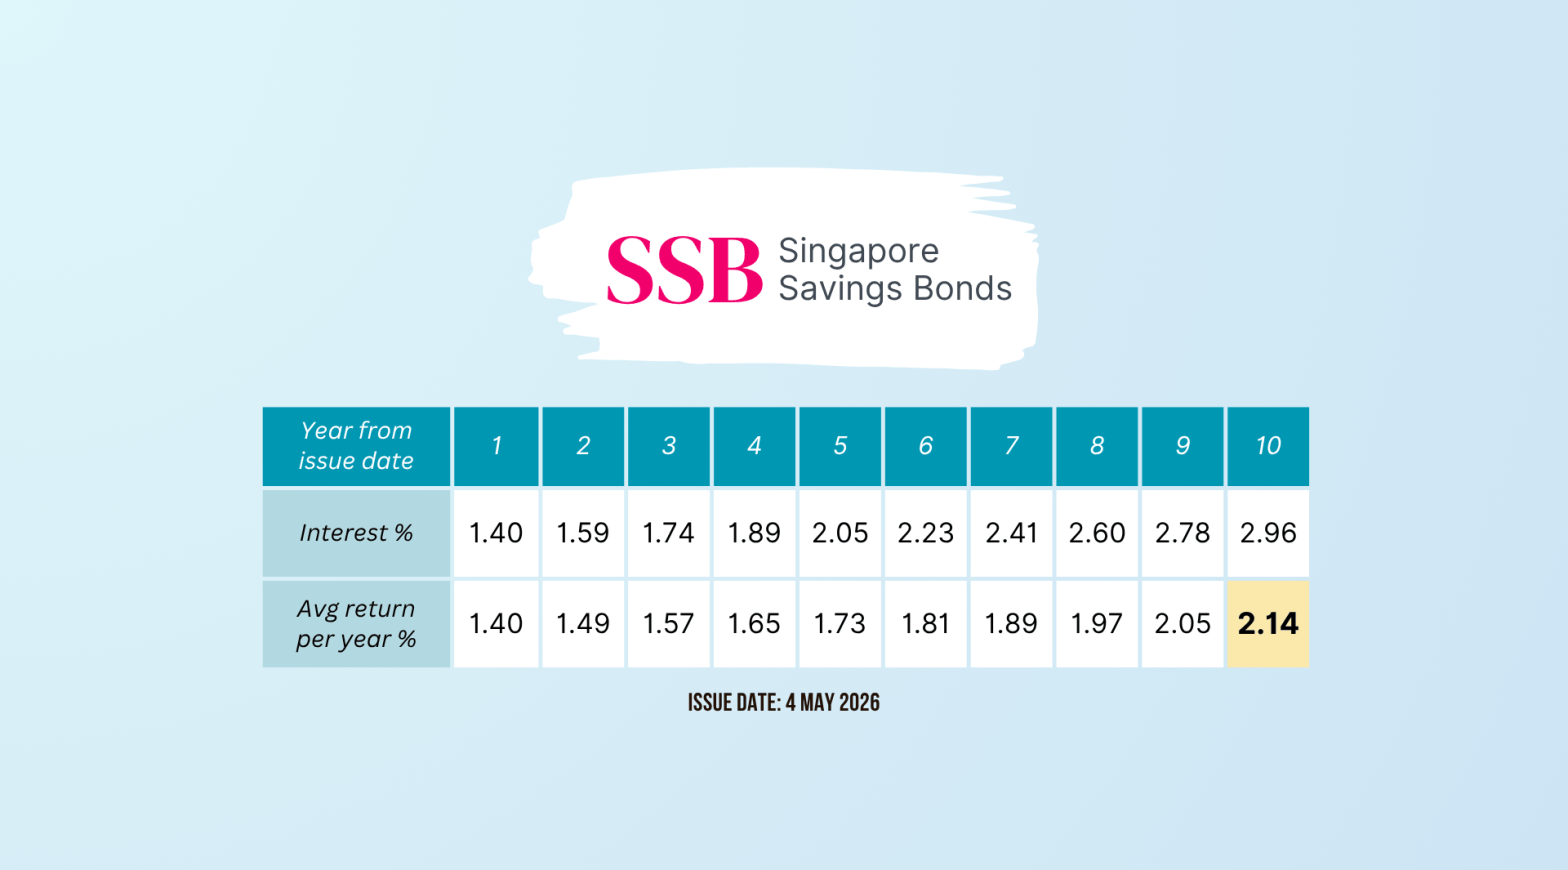
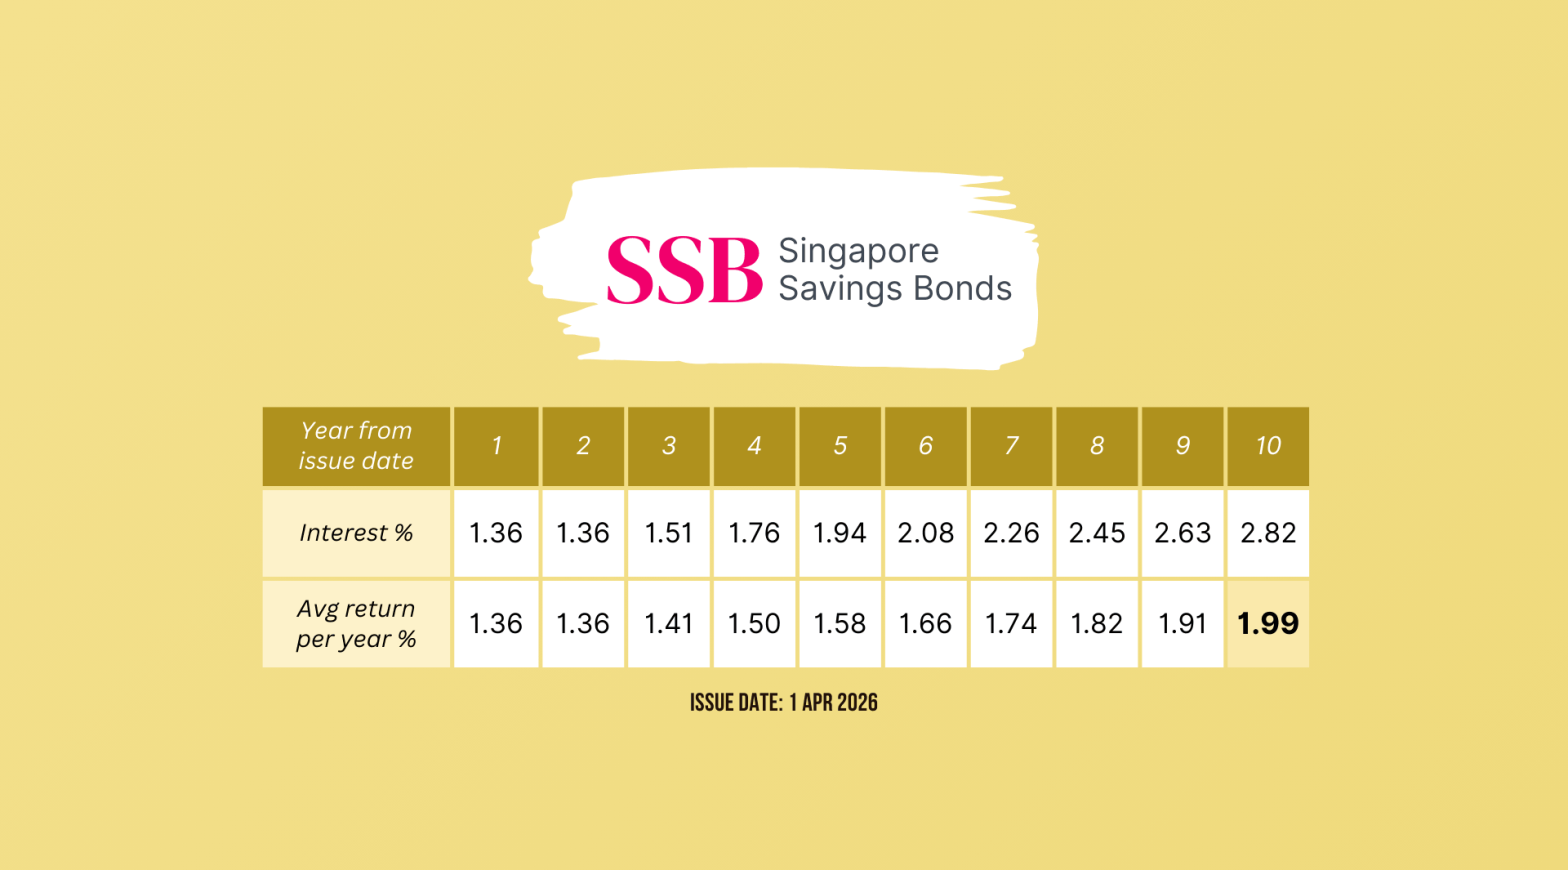
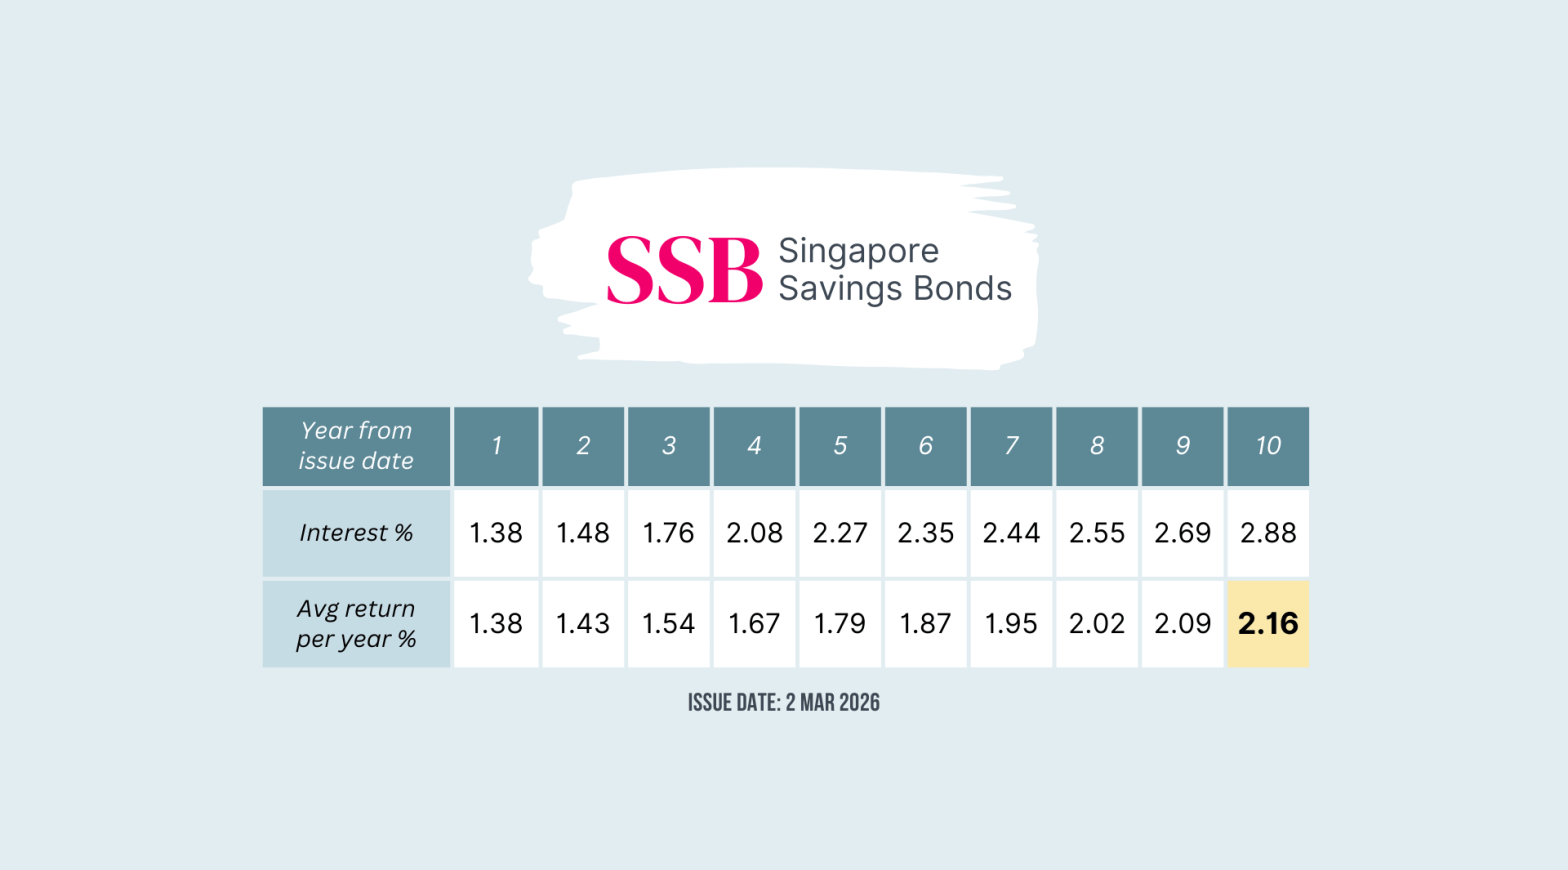
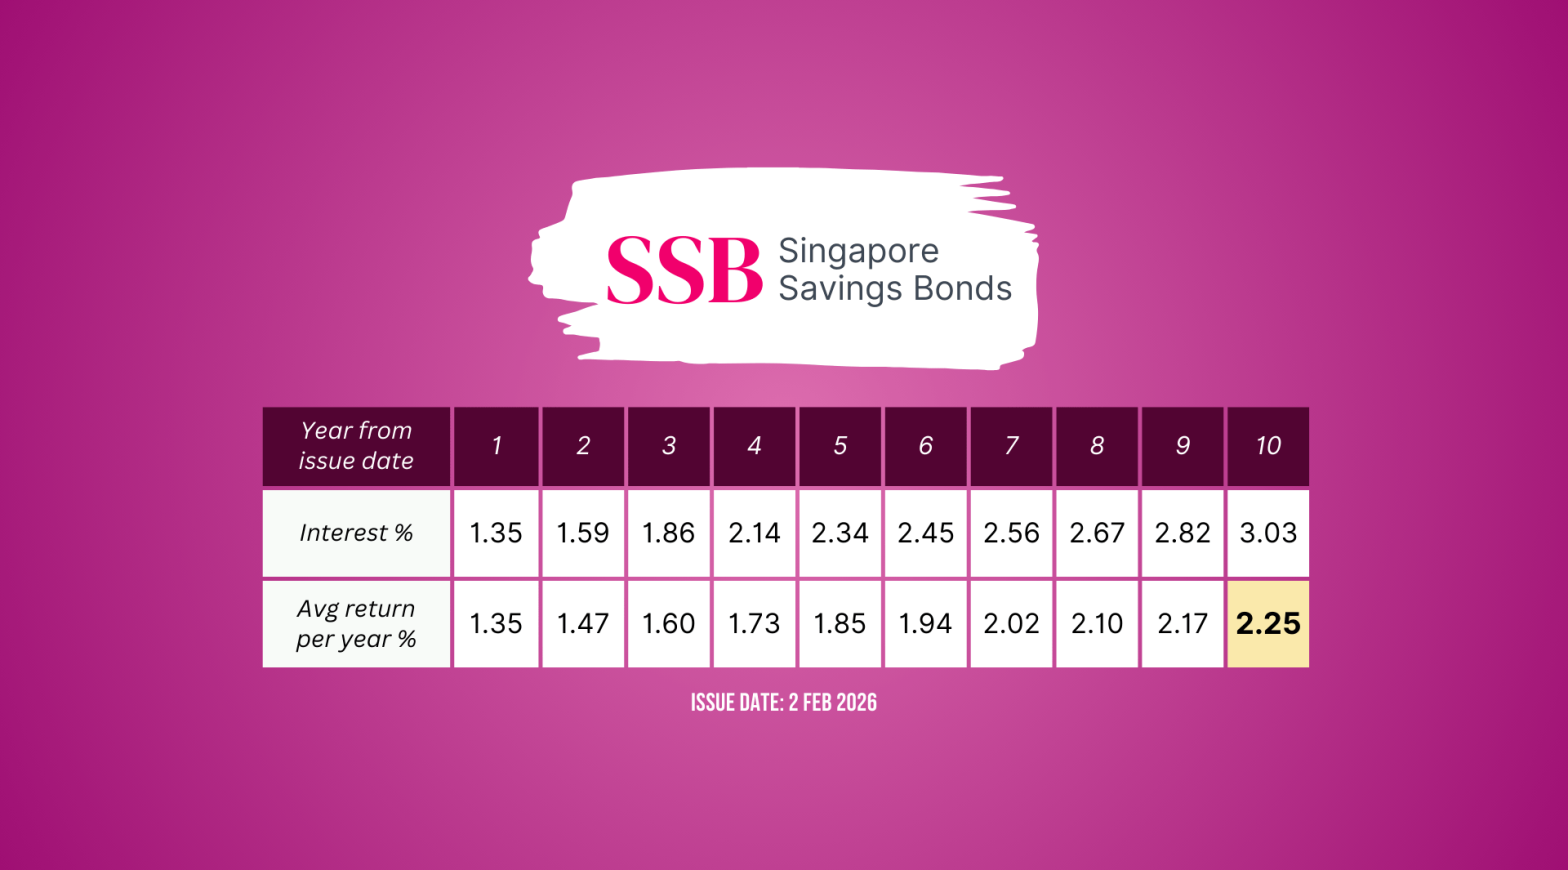
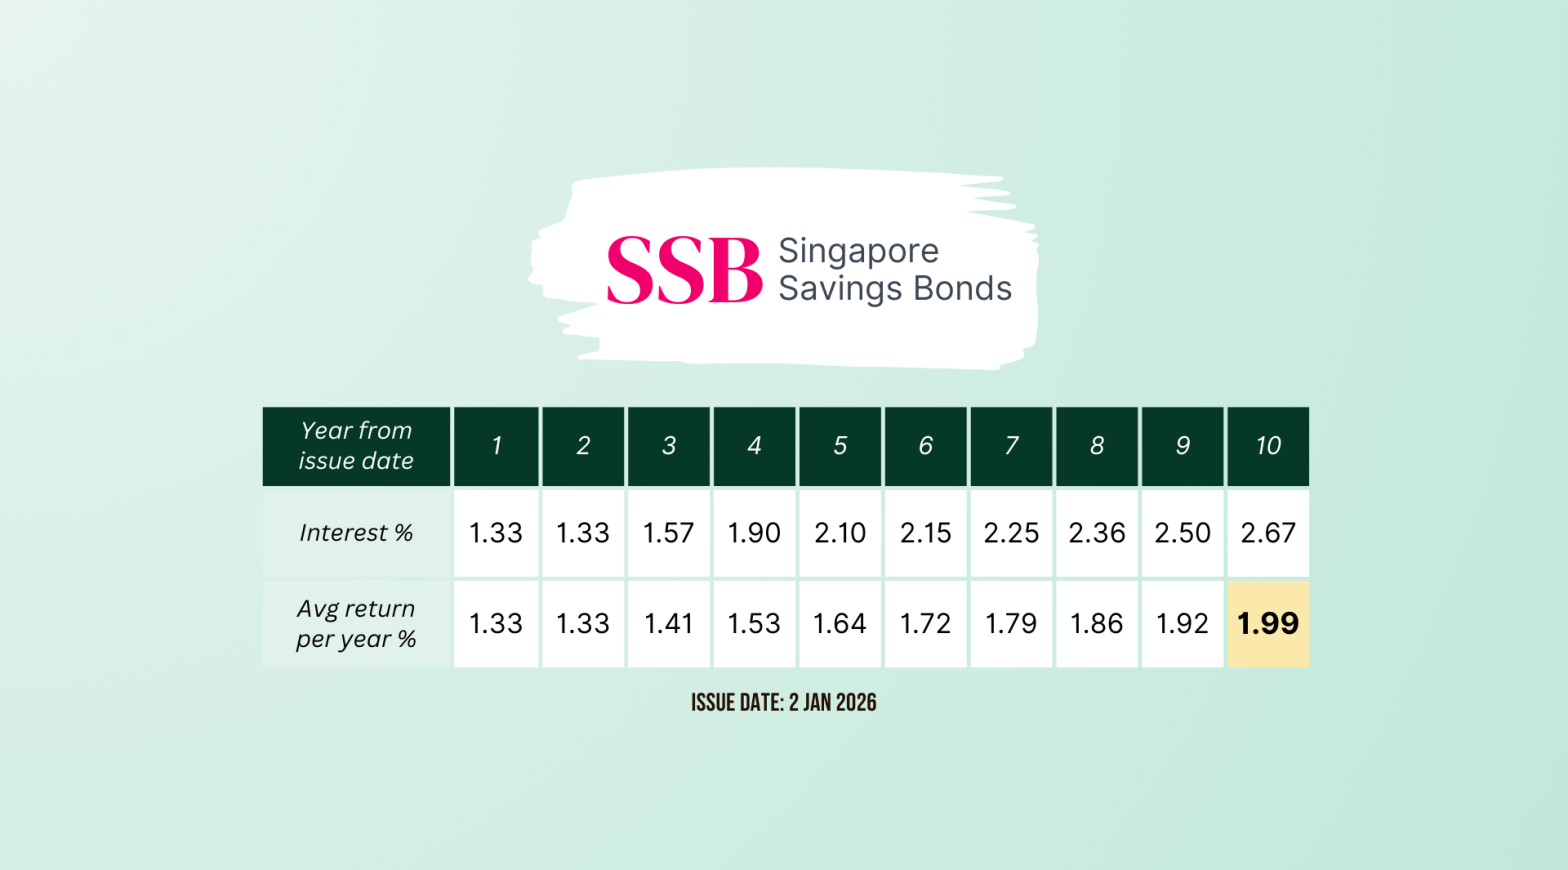
We think the 1-year T-bill is still a decent option for investing our CPF money. For our cash, we no longer use the 1-year T-bill to park it. With the expectation that interest rates will reverse this year, we have moved most of our short-term cash into Singapore Savings Bonds (SSB) to lock in this higher rate for much longer: ten years! SSB also allows monthly redemption, making it the more liquid option.
We will continue to use 6-month T-bills to park a smaller portion of our short-term cash and benefit from higher short-term rates.
What do you think? Are you interested in applying for the next 1-year T-bill? If yes, you may follow our guide on how to buy T-bills.
If you plan on using CPF, you can estimate the additional interest you may earn with our CPF T-bill calculator.