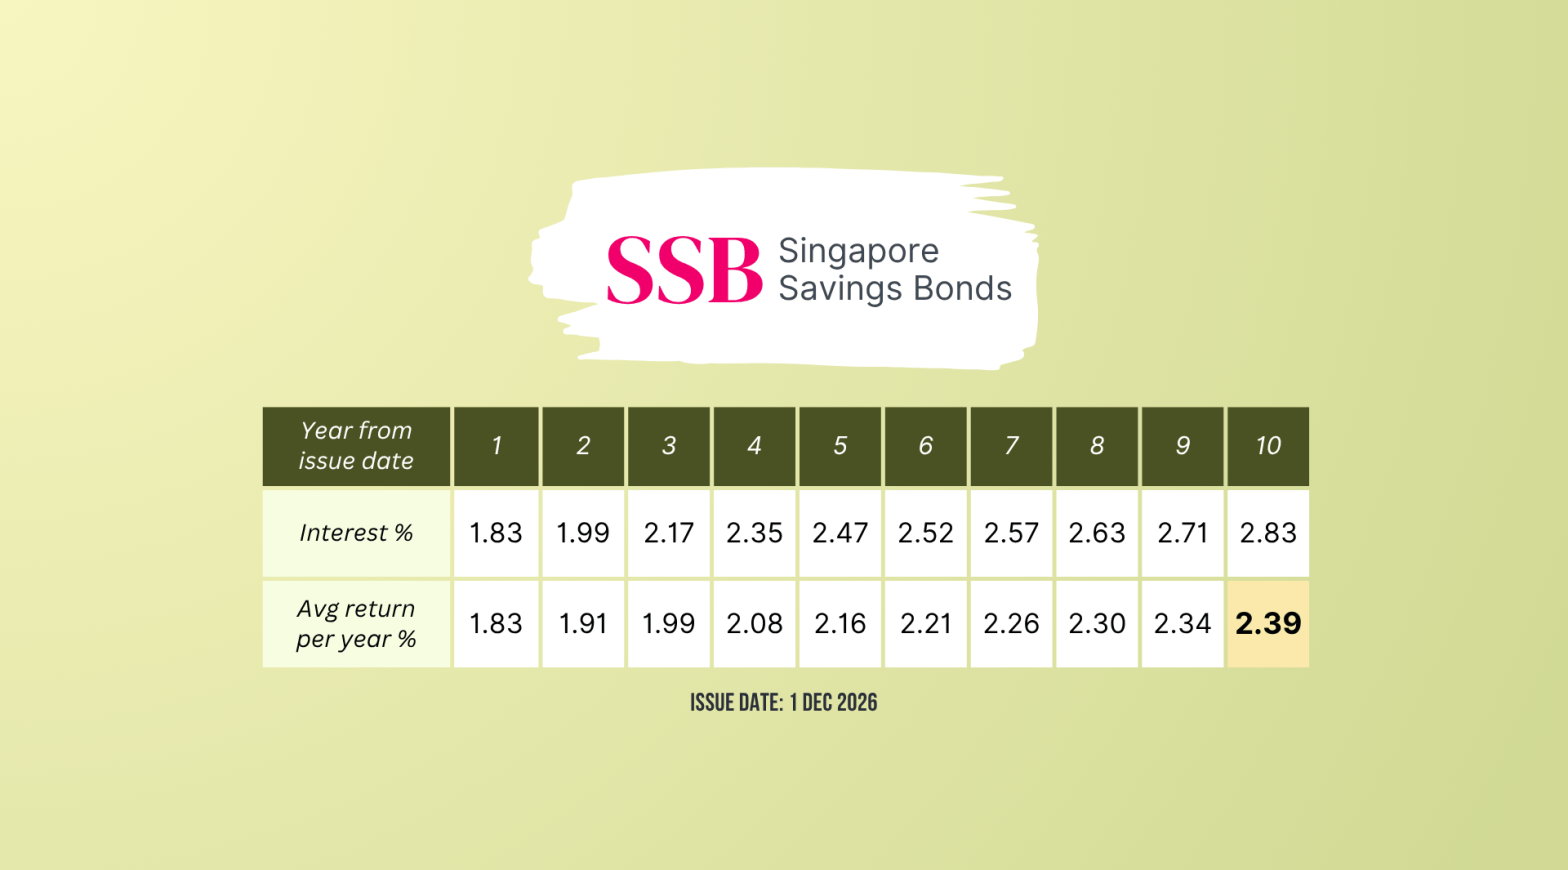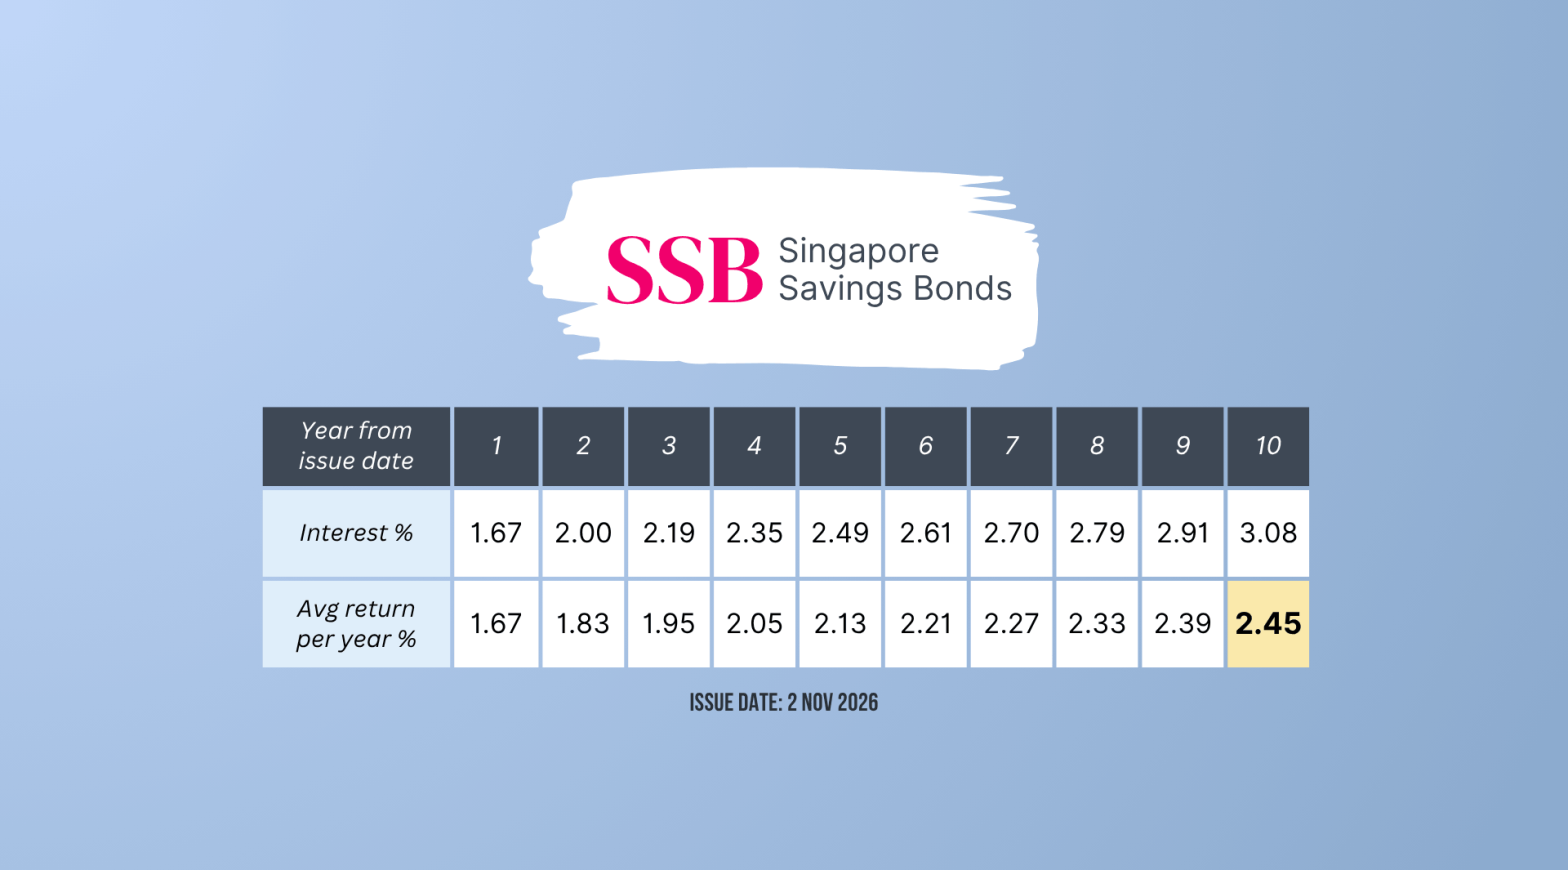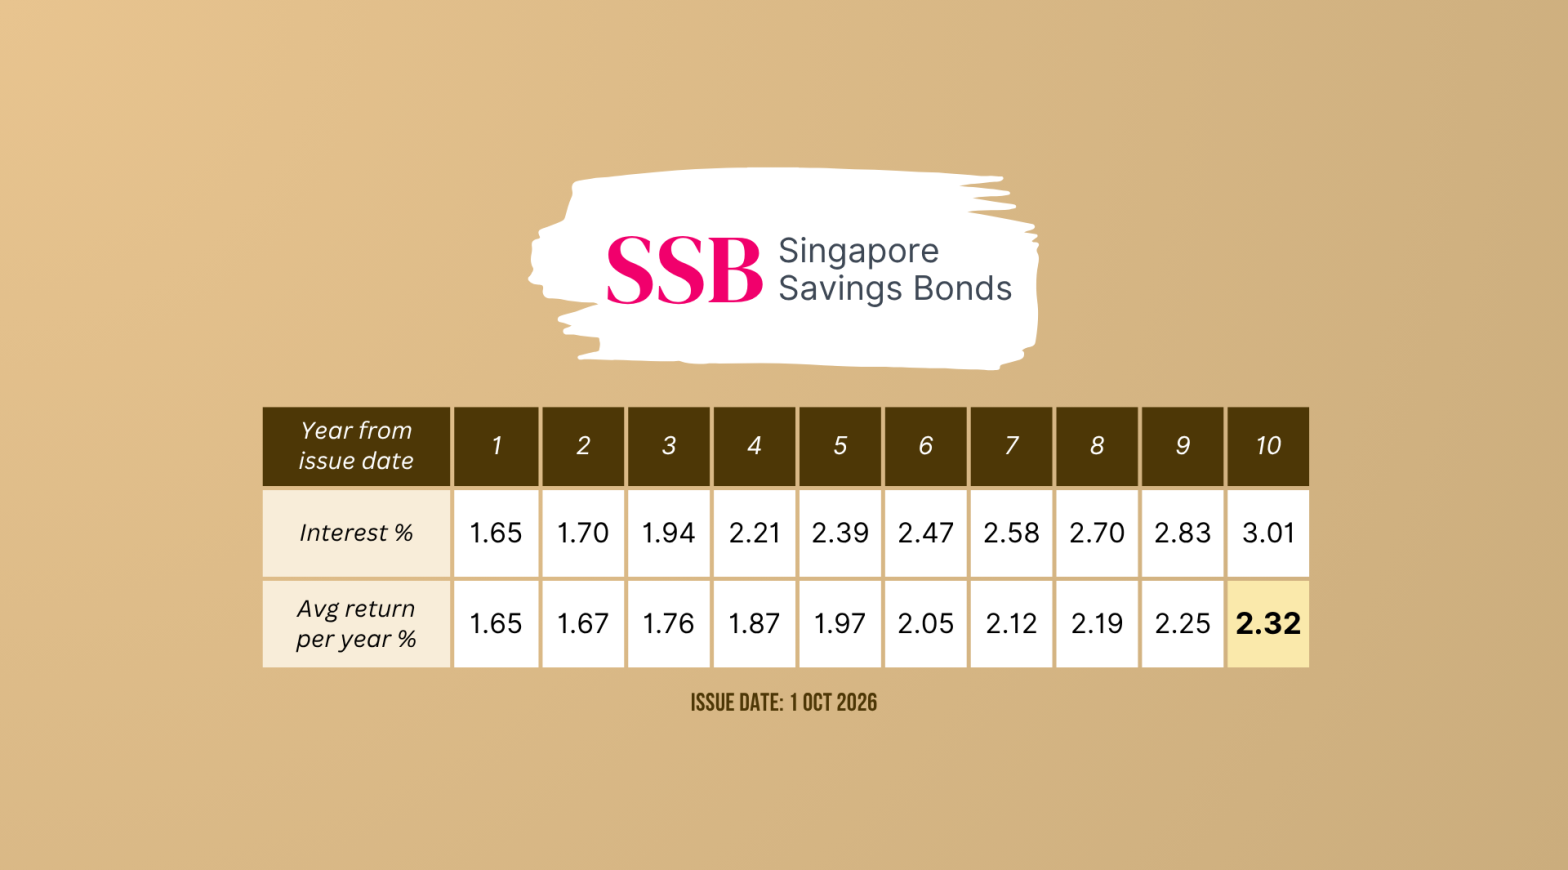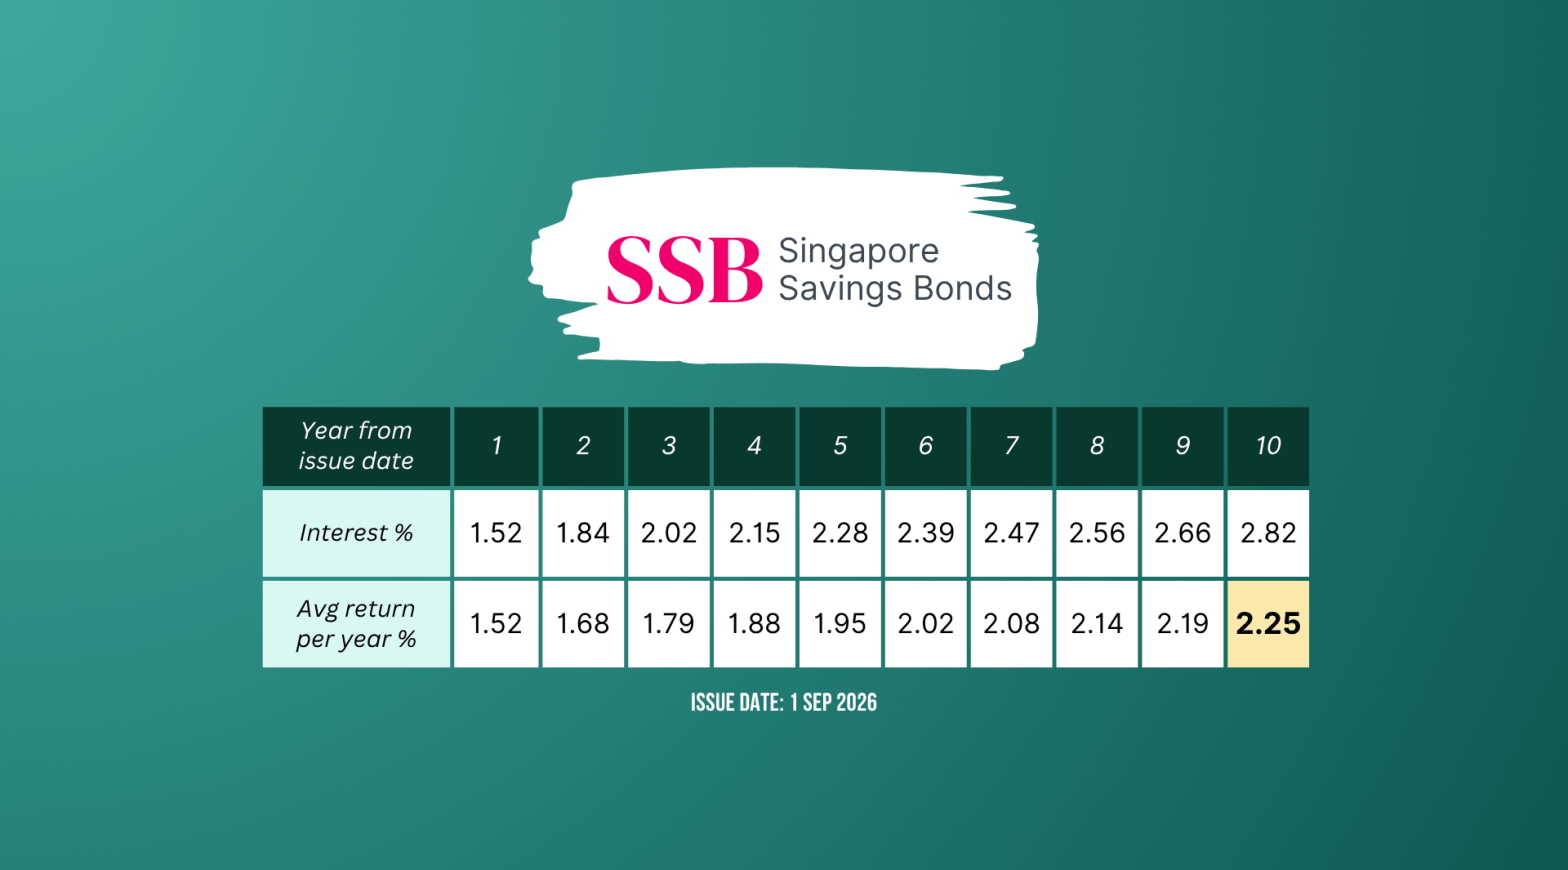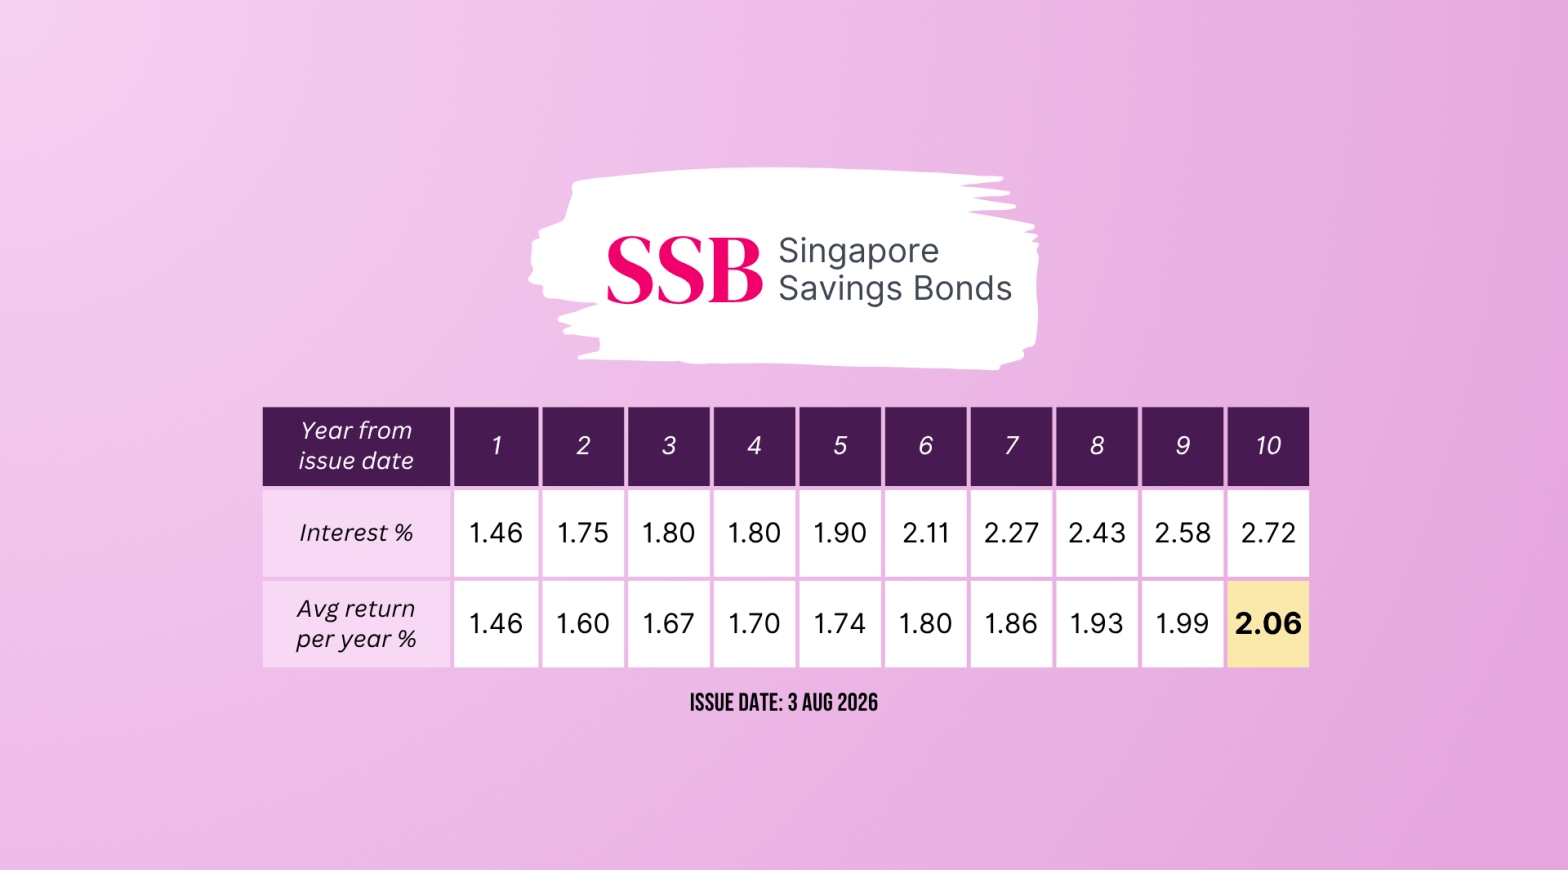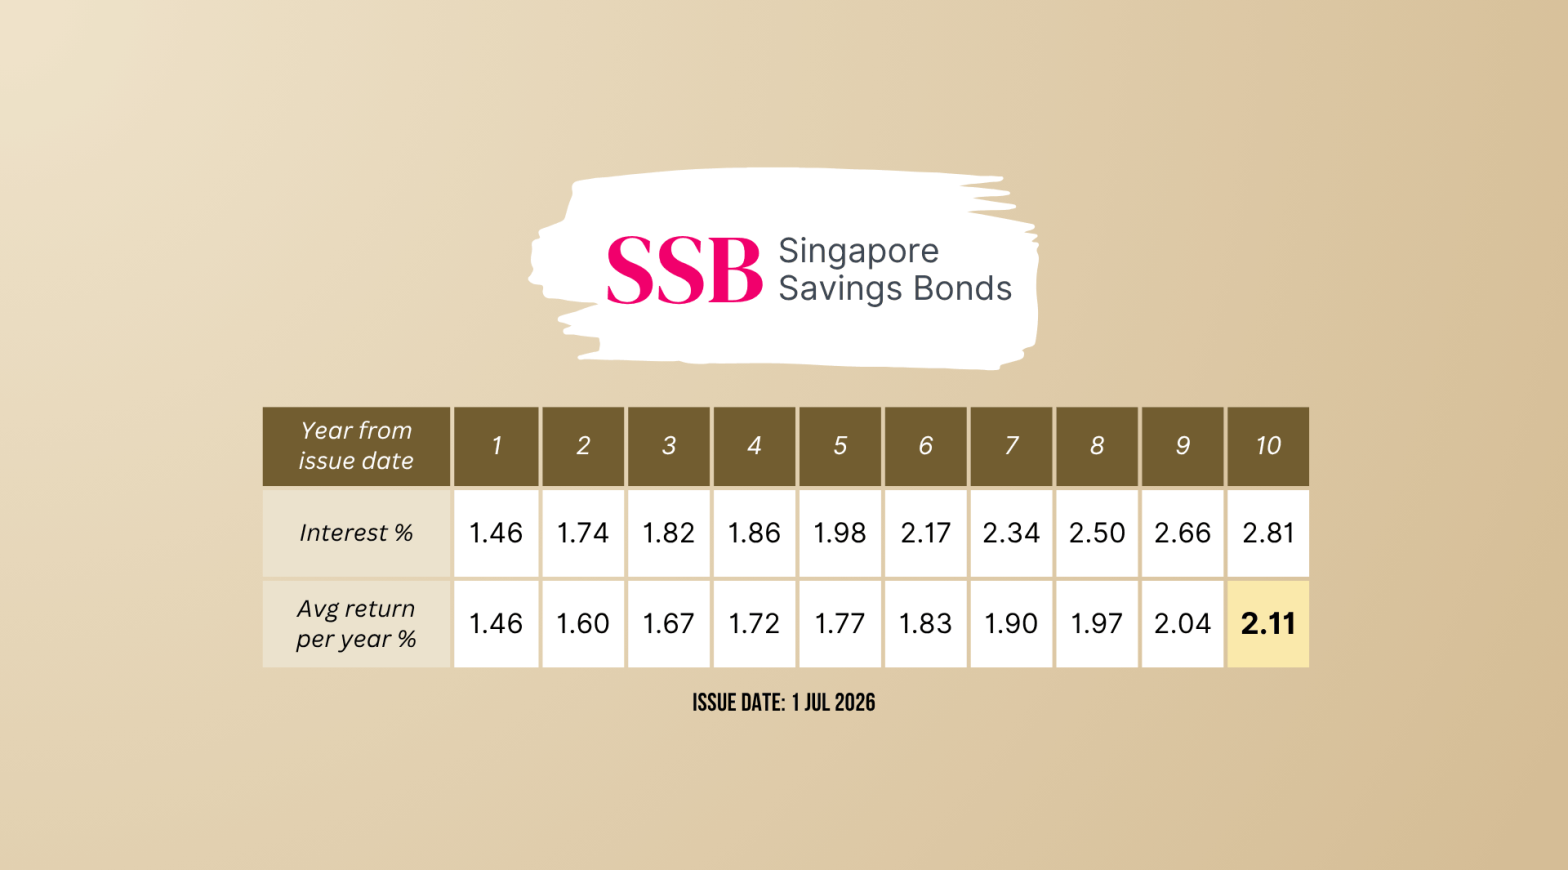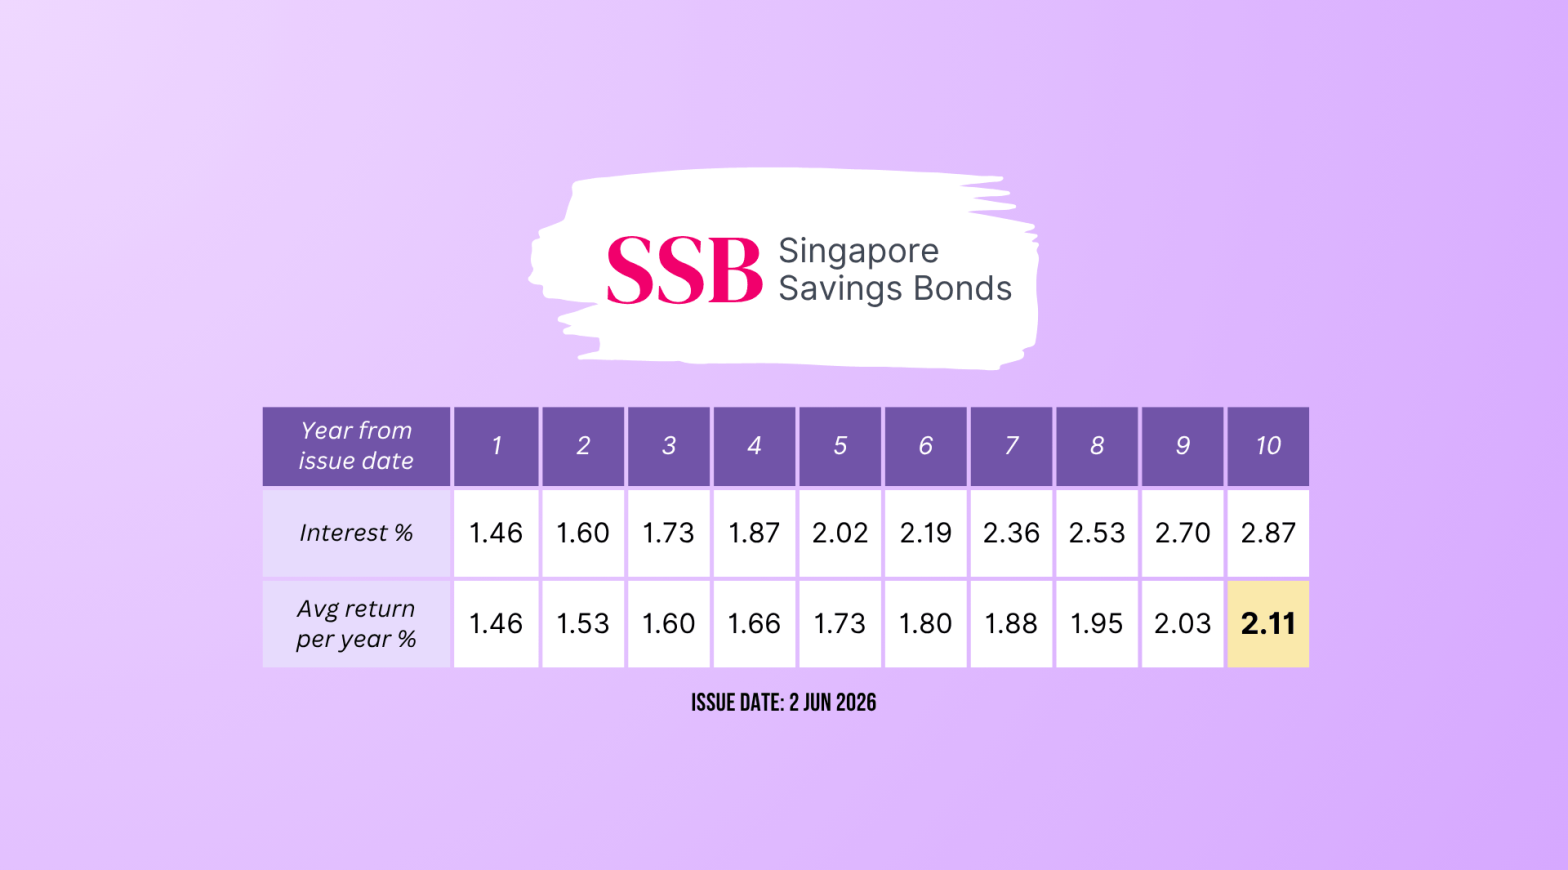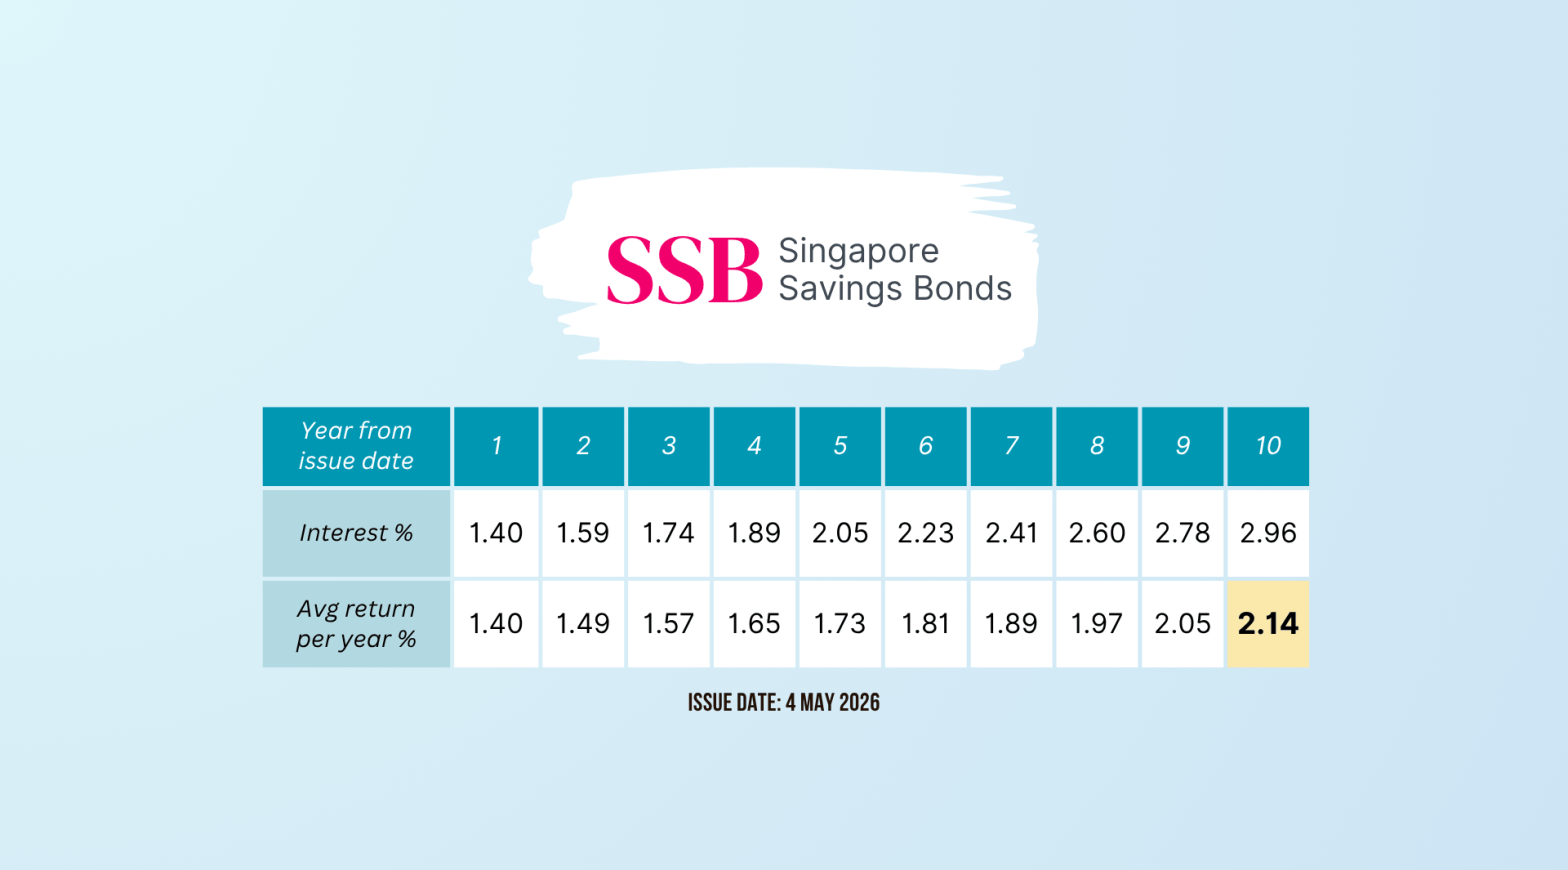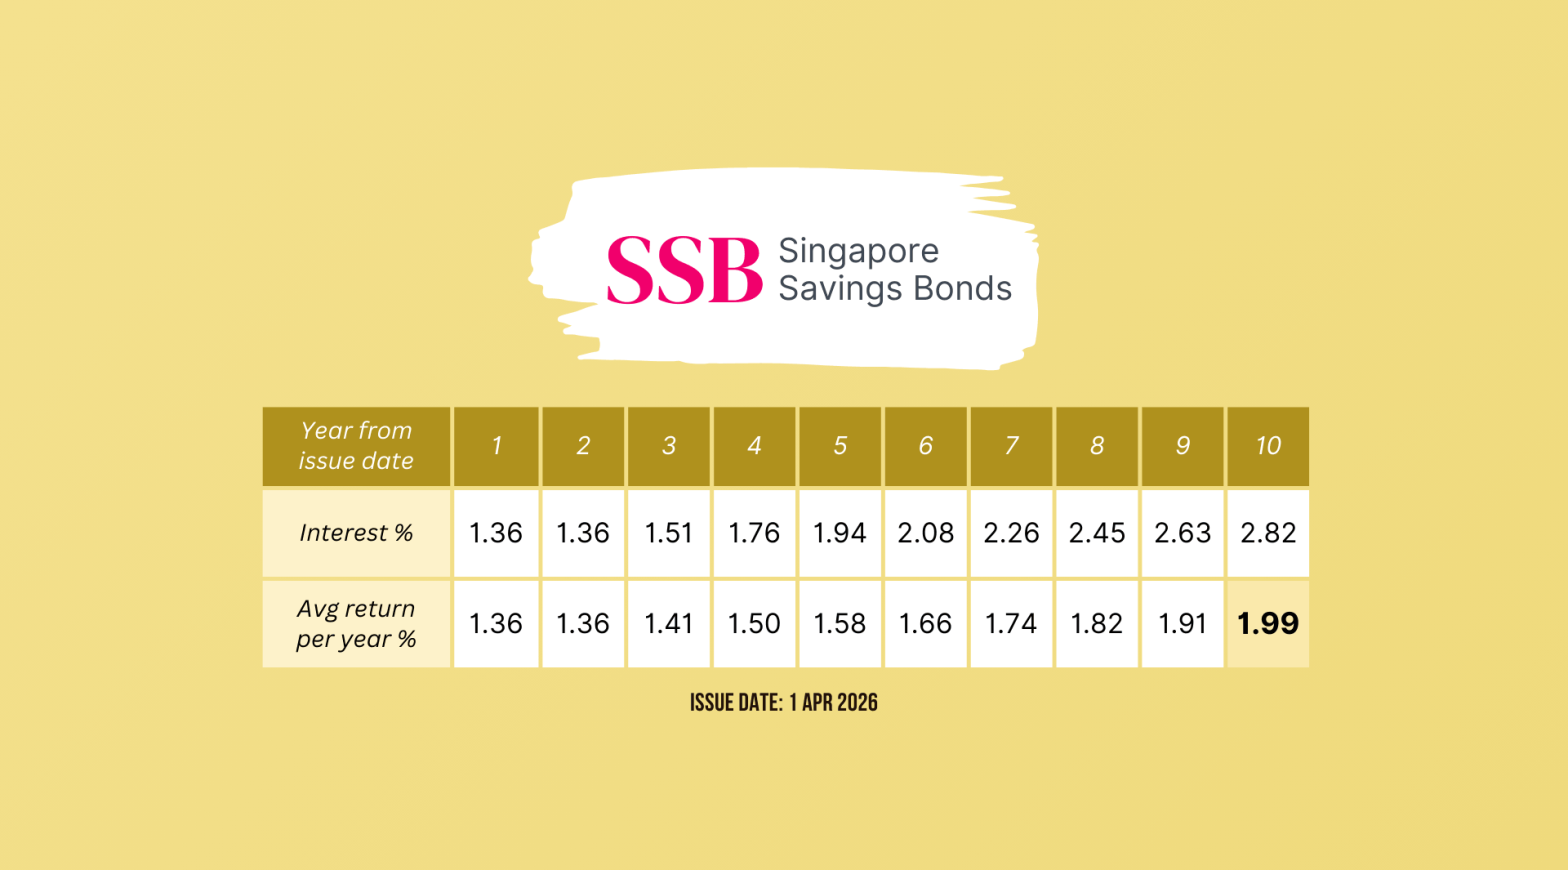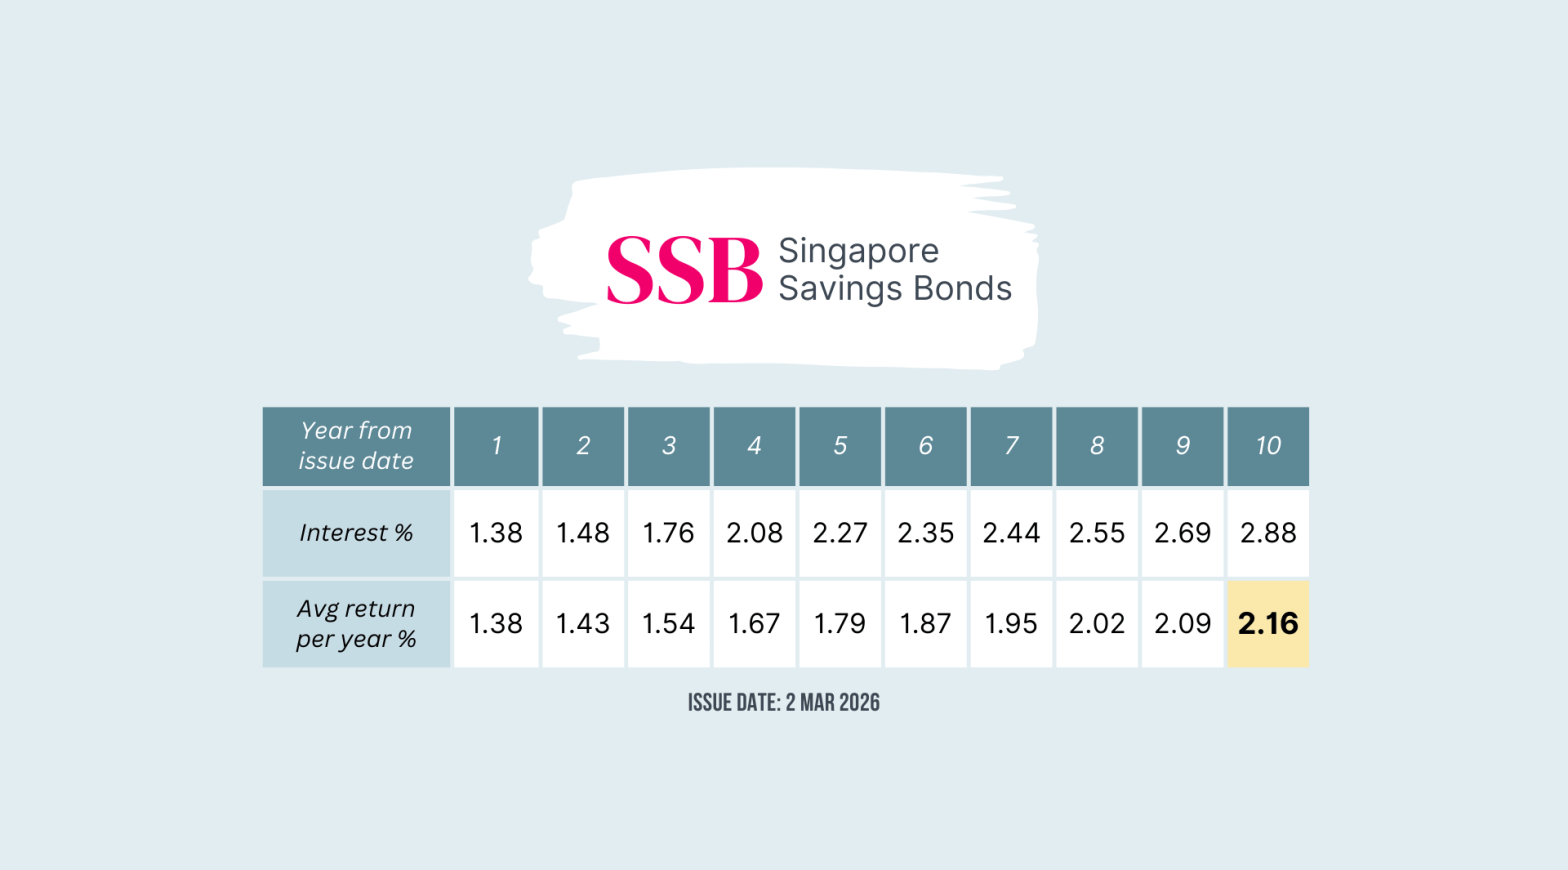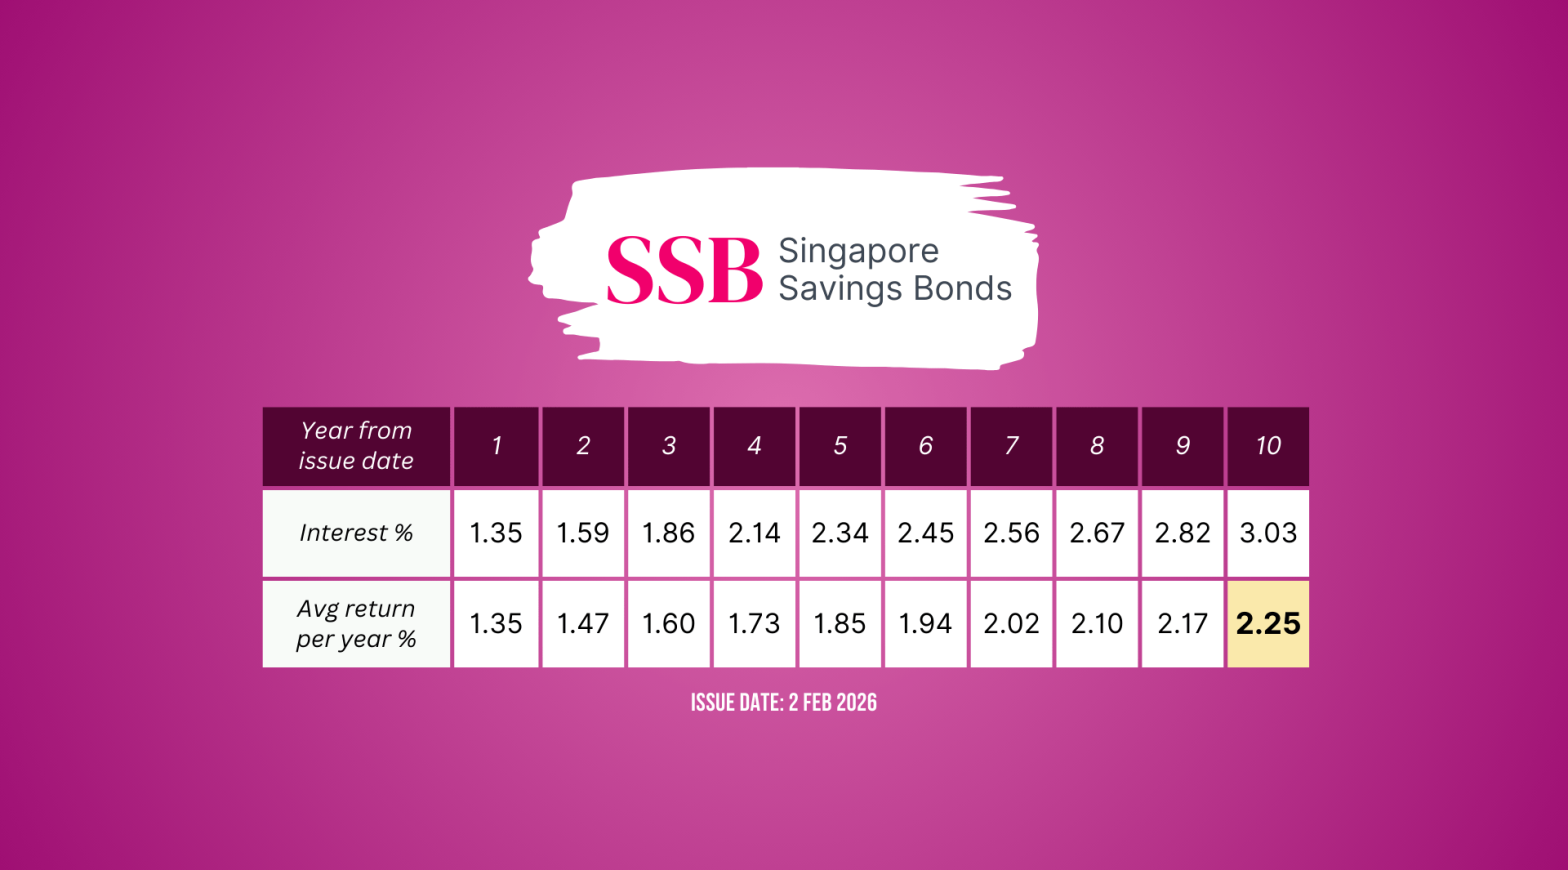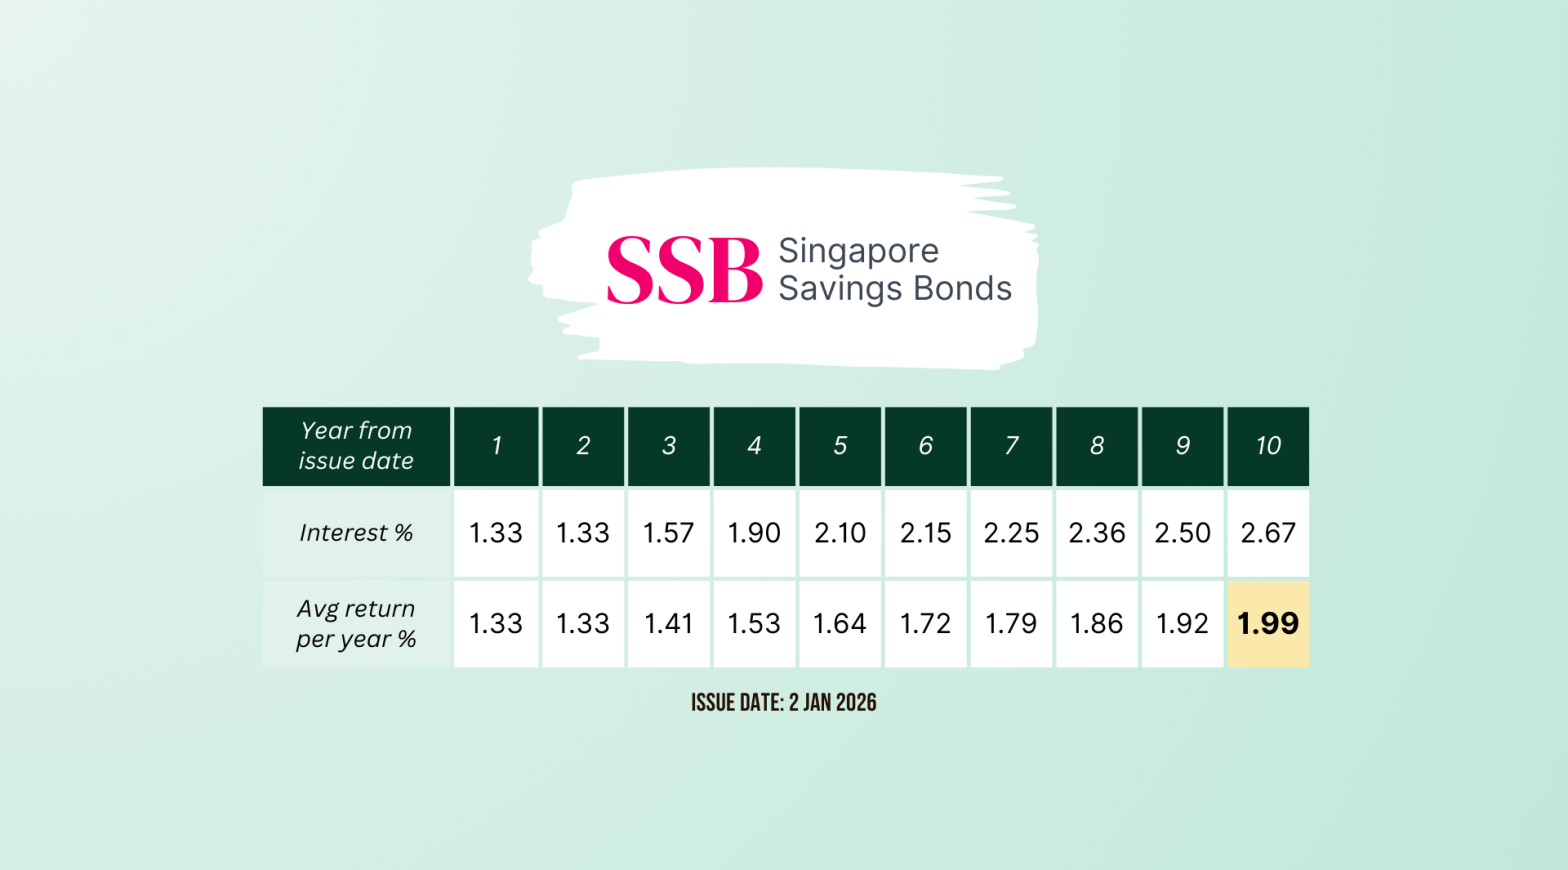

MAS announced the latest SSB June 2023 offering, and many investors were somewhat disappointed with the return. The first-year return is 2.81%, and the 10-year average is also 2.81%. Here is the interest rate breakdown:

The latest Singapore Savings Bond offering saw the first-year and the average 10-year interest rates drop significantly from >3% to 2.81%. This drop is not a surprise because it is in line with other fixed-income instruments such as SGS, T-Bills, and fixed deposits, which have also experienced a decline in their interest offerings recently. Is SSB still a good investment option with this lower interest rate?
Key Takeaways
- SSB June 2023 rates fell compared to last month’s offering. This aligns with the other fixed-income products and the current macroeconomic backdrop.
- For short-term investors, T-Bills, fixed deposits, and money market accounts offer much higher interest rates.
- For long-term investors, the rate is still one of the highest in recent years. With the market expecting long-term interest rates to decline, this could be your chance to lock in the relatively high rate.
- With the current low SSB demand, this month’s offering can be a good chance for you to roll over older SSBs yielding less than 2.81%.
Macroeconomic Background
Inflation has been cooling down recently, with the latest US CPI for March 2023 at 5%.

The consistent decline in CPI readings over the past several months supports the thesis that disinflation has begun. As a result, the market has been expecting the Federal Reserve to make the final hike (or two) before reaching its terminal interest rate target, keep rates there for a few months, and then start to pivot.

With the recent banking turmoil and possible impending recession, the market believes that the likelihood of further rate hikes beyond what is already priced in is relatively small. Because of that, the market has been pricing a lower long-term interest rate as the Fed normalizes its interest rate policy back to near its target inflation level of 2%.
Declining SSB Demand
The demand for SSB has declined in the past several issuances. All 2023 issuances have seen relatively low demand, with all applicants getting their full allotment or a high enough ceiling. In the past two issuances, although interest rates were still above 3%, all applicants still received their full allotment. We expect SSB demand to decline further this month with the lower rate.
Is it still good to invest in SSB?
SSB is a long-term 10-yr bond issued by the Singapore government, but with the flexibility to withdraw every month without penalty. Many of our readers fall into two camps: those who want to invest for the long term (up to 10 years), and those who want a relatively high-yielding, liquid, and safe asset for extra cash they don’t yet know where to deploy. The latter sees SSB as a short-term investment due to its flexibility. Let’s examine both cases to see whether SSB is still a good option for investors.
1-Year Rate
The first-year SSB rate stands at 2.81%, significantly lower than T-Bills and fixed deposit rates, which still offer much higher than 3%. However, SSB offers higher flexibility, allowing investors to withdraw in any month while still earning the accrued interest without penalty. If you buy an SSB to park cash short-term, you can assess whether you need to use the money soon. If you are okay with locking your money for 3-12 months, T-Bills and fixed deposits offer a much higher interest rate. But if you need relatively liquid access to your money, SSB can still be a good choice, as 2.81% is a decent return. In our opinion, the interest rate difference, though noticeable, won’t matter much if you plan to hold it short term.
Average 10-Year Rate
For long-term investors, the average 10-yr yield is what you want to look for. Though has fallen quite a bit, 2.81% is still much higher than the yields we saw earlier last year.

If you are a long-term investor who prefers stability and flexibility from SSB, the latest SSB offering still offers a decent value. With the market expecting long-term interest rates to fall further, it may be a good idea to lock in now and enjoy this relatively high rate for the next ten years.
The beauty of SSB is that it lets you roll your previous SSB, which yields less than the current offering; so if interest rates continue to rise, you can roll it into a later one with a higher yield. You can keep rolling if interest rates keep rising. If interest rates decline, the good news is that you have locked in your SSB now and can enjoy higher rates for the next ten years.
Roll Over Older SSB with Lower Yield
As we expect this month’s offering to have lower demand, this is a great opportunity to roll over our previous SSBs with lower yields. If demand is low, we can get the full allocation from our previous SSB without worrying about reaching the ceiling in this month’s offering. Consider rolling into this month’s SSB if you have older SSBs yielding much lower than 2.81%.
Summary
The latest SSB June 2023 interest rate decline aligns with other fixed-income products such as fixed deposits and T-Bills. The market expects the long-term interest rate to decline further as the Federal Reserve reaches its terminal interest rate target and starts pivoting.
If you are holding SSB as a short-term instrument to park extra cash, focus on the 1-yr rate, which currently stands at 2.81%. This rate is significantly lower than T-Bills or fixed deposit rates but offers more flexibility, with monthly withdrawals and accrued interest. In our opinion, the 1-yr rate is still decent given the safety and flexibility SSB offers. Depending on your needs, if you are okay with locking your money for a bit longer, 3-12 months, you may consider T-Bills and fixed deposits. Otherwise, SSB is a solid option.
For long-term investors, you should look at the 10-yr average rate, which currently stands at 2.81%. Although this rate is lower than the previous offering, it is still much higher than in recent years. We believe the current 10-yr average rate remains a decent option for investors seeking a safe, flexible investment.
If you are interested in investing in this SSB June 2023 offering, please take note of the following application timeline: